Clubbing of income from gifted property failed where the claim surfaced after reassessment limitation, sustaining capital-gains assessment in spouse's...
Employee stock-option discount qualifies as revenue expenditure, while royalty and service comparables require reliable functional and transactional b...
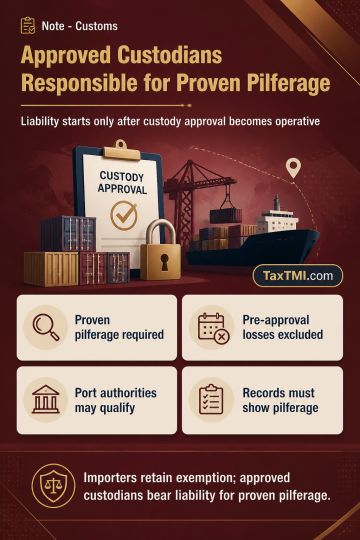
Customs-duty liability for pilfered imported goods arises under Section 45(3) only where the goods were unloaded in a customs area and pilfered while in the custody of a person approved under Section 45(1). Approval is a necessary precondition, so liability does not extend to pilferage before the approval became operative. A statutory port authority may be an approved custodian, and its civil responsibilities as bailee do not displace its separate revenue liability. The importer's duty exemption for pilferage operates alongside the custodian's statutory obligation. Pilferage, rather than an unexplained cargo discrepancy or non-pilferage loss, must be established through contemporaneous custody and security records.
Customs-duty liability for pilfered imported goods arises under Section 45(3) only where the goods were unloaded in a customs area and pilfered while in the custody of a person approved under Section 45(1). Approval is a necessary precondition, so liability does not extend to pilferage before the approval became operative. A statutory port authority may be an approved custodian, and its civil responsibilities as bailee do not displace its separate revenue liability. The importer's duty exemption for pilferage operates alongside the custodian's statutory obligation. Pilferage, rather than an unexplained cargo discrepancy or non-pilferage loss, must be established through contemporaneous custody and security records.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4901