Independent manufacturing undertaking eligibility preserves Section 80IA/80IB deductions, while machinery kept ready for use qualifies for depreciatio...
Assessing Officer Satisfaction Requirement Bars Penalty for Cash Receipt in Immovable-Property Sale Cases Where Initiation Lacks Recorded Satisfaction...
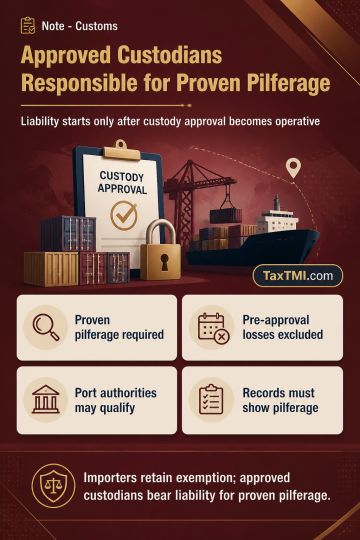
Customs-duty liability for pilfered imported goods arises under Section 45(3) only where the goods were unloaded in a customs area and pilfered while in the custody of a person approved under Section 45(1). Approval is a necessary precondition, so liability does not extend to pilferage before the approval became operative. A statutory port authority may be an approved custodian, and its civil responsibilities as bailee do not displace its separate revenue liability. The importer's duty exemption for pilferage operates alongside the custodian's statutory obligation. Pilferage, rather than an unexplained cargo discrepancy or non-pilferage loss, must be established through contemporaneous custody and security records.
Customs-duty liability for pilfered imported goods arises under Section 45(3) only where the goods were unloaded in a customs area and pilfered while in the custody of a person approved under Section 45(1). Approval is a necessary precondition, so liability does not extend to pilferage before the approval became operative. A statutory port authority may be an approved custodian, and its civil responsibilities as bailee do not displace its separate revenue liability. The importer's duty exemption for pilferage operates alongside the custodian's statutory obligation. Pilferage, rather than an unexplained cargo discrepancy or non-pilferage loss, must be established through contemporaneous custody and security records.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4913