Clubbing of income from gifted property failed where the claim surfaced after reassessment limitation, sustaining capital-gains assessment in spouse's...
Employee stock-option discount qualifies as revenue expenditure, while royalty and service comparables require reliable functional and transactional b...
Page of 4902
Press 'Enter' after typing page number.
121 to 140 of 98021 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
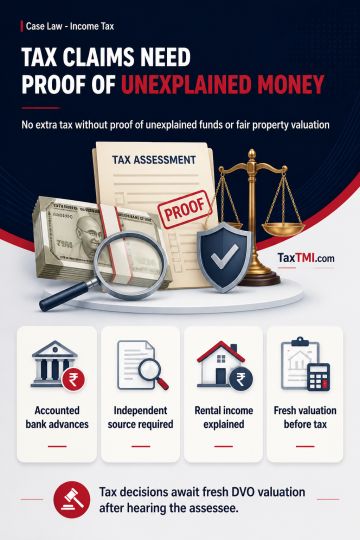
Builder-financing additions for alleged cash receipts or payments cannot be sustained as unexplained money or unexplained investment where the amount represents return of an accounted banking-channel advance and no independent unexplained source or accretion is established. Alleged interest income cannot be inferred solely from a purported financing arrangement where property acquisitions were explained as investments generating rental income and capital gains. Stamp-duty valuation provisions apply to immovable-property acquisitions irrespective of their characterisation as builder financing. Where the stamp-duty value of under-construction property is disputed, fair market value must be determined through the statutory valuation mechanism before taxability and quantum are decided; the valuation issues require DVO-based fresh determination after hearing the assessee.
Builder-financing additions for alleged cash receipts or payments cannot be sustained as unexplained money or unexplained investment where the amount represents return of an accounted banking-channel advance and no independent unexplained source or accretion is established. Alleged interest income cannot be inferred solely from a purported financing arrangement where property acquisitions were explained as investments generating rental income and capital gains. Stamp-duty valuation provisions apply to immovable-property acquisitions irrespective of their characterisation as builder financing. Where the stamp-duty value of under-construction property is disputed, fair market value must be determined through the statutory valuation mechanism before taxability and quantum are decided; the valuation issues require DVO-based fresh determination after hearing the assessee.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4902