Income Declaration Scheme declarations can evidence share-capital sources, while round-tripped funds and cash-linked credits require further verificat...
Permanent establishment tests: independent subsidiary premises and principal-to-principal dealings did not create Indian taxability for offshore suppl...
Valuation Officer estimates govern property-value additions once statutory valuation is invoked, requiring fresh consideration of objections and compa...
Page of 4920
Press 'Enter' after typing page number.
581 to 600 of 98394 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
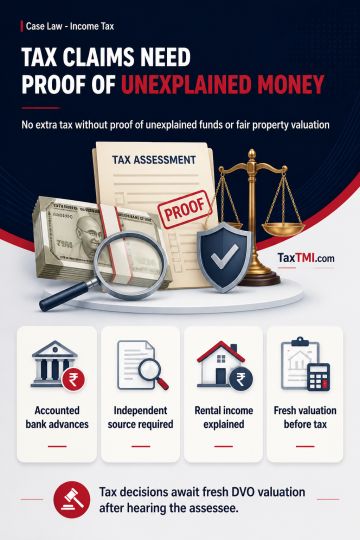
Builder-financing additions for alleged cash receipts or payments cannot be sustained as unexplained money or unexplained investment where the amount represents return of an accounted banking-channel advance and no independent unexplained source or accretion is established. Alleged interest income cannot be inferred solely from a purported financing arrangement where property acquisitions were explained as investments generating rental income and capital gains. Stamp-duty valuation provisions apply to immovable-property acquisitions irrespective of their characterisation as builder financing. Where the stamp-duty value of under-construction property is disputed, fair market value must be determined through the statutory valuation mechanism before taxability and quantum are decided; the valuation issues require DVO-based fresh determination after hearing the assessee.
Builder-financing additions for alleged cash receipts or payments cannot be sustained as unexplained money or unexplained investment where the amount represents return of an accounted banking-channel advance and no independent unexplained source or accretion is established. Alleged interest income cannot be inferred solely from a purported financing arrangement where property acquisitions were explained as investments generating rental income and capital gains. Stamp-duty valuation provisions apply to immovable-property acquisitions irrespective of their characterisation as builder financing. Where the stamp-duty value of under-construction property is disputed, fair market value must be determined through the statutory valuation mechanism before taxability and quantum are decided; the valuation issues require DVO-based fresh determination after hearing the assessee.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4920