Loading...

⚠ ✕
❮ Top
☎ Help
☰
×

By creating an account you can:

Logo TaxTMI
Call Us / Help / Feedback✕

Contact Us At :

✉ E-mail: [email protected]

✆ Call / WhatsApp at: +91 99117 96707

For more information, Check Contact Us

FAQs :

To know Frequently Asked Questions, Check FAQs

Most Asked Video Tutorials :

For more tutorials, Check Video Tutorials

Submit Feedback/Suggestion :

Email :
Please provide your email address so we can follow up on your feedback.
Category :
Description :
Min 15 characters 0/2000
Make Most of Text Search ✕
  1. Checkout this video tutorial: How to search effectively on TaxTMI.
  2. Put words in double quotes for exact word search, eg: "income tax"
  3. Avoid noise words such as : 'and, of, the, a'
  4. Sort by Relevance to get the most relevant document.
  5. Press Enter to add multiple terms/multiple phrases, and then click on Search to Search.
  6. Text Search
  7. The system will try to fetch results that contains ALL your words.
  8. Once you add keywords, you'll see a new 'Search In' filter that makes your results even more precise.
  9. Text Search
╳
Add to...
You have not created any category. Kindly create one to bookmark this item!
✕
Create New Category
Hide
Title :
Description :
❮❮ Hide
❮ Default View
Expand ❯❯
Close ✕
🔎 Filters / Advanced Search ❯
TEXT

Press 'Enter' to add multiple search terms. Rules for Better Search

Search In
Main Text + AI Text ❯
  • Main Text
  • Main Text + AI Text
  • AI Text
Law:
---- All Laws---- ❯
  • ---- All Laws----
  • Income Tax
  • Direct Taxes
  • Benami Property
  • Central GST Laws
  • SGST - State GST Laws
  • Customs
  • FTP - Foreign Trade Policy
  • SEZ - Special Economic Zone
  • FEMA - Foreign Exchange Management
  • Companies Law
  • SEBI - Securities & Exchange Board of India
  • IBC - Insolvency and Bankruptcy
  • Law of Competition
  • PMLA - Money-Laundering
  • Indian Laws
  • Bill / Finance Bills
  • Wealth Tax
  • Service Tax
  • Central Excise
  • VAT / Sales Tax
Month:
---- All Months ---- ❯
  • ---- All Months ----
  • January
  • February
  • March
  • April
  • May
  • June
  • July
  • August
  • September
  • October
  • November
  • December
Year:
---- All Years ---- ❯
  • ---- All Years ----
  • 2026
  • 2025
  • 2024
  • 2023
  • 2022
  • 2021
  • 2020
  • 2019
  • 2018
  • 2017
  • 2016
  • 2015
  • 2014
  • 2013
  • 2012
  • 2011
Sort By: ?
In Sort By 'Default', exact matches for text search are shown at the top, followed by the remaining results in their regular order.
Relevance Default Date
☰   Show Results ❯
    Identical GST legal questions require transfer of related refund appeals to the Principal Bench for consolidated hearing.
    Input tax credit on laptop purchases survives retrospective supplier-registration cancellation where actual tax payment is established.
    Effective hearing rights prevent same-day confiscation orders when authorities grant time for a written response.
    Statutory limits on GST appeal delay condonation remain binding, while restored registrations can make departmental challenges infructuous.
    Delayed judgment pronouncement alone does not invalidate Tribunal orders, while rectification cannot reopen evidence or negate confiscation-related pe...
    Philanthropic hospital approval turns on medical-purpose application of funds, not revenue surplus or free-treatment ratios alone.
    Prospective software royalty clarification prevents tax-deduction disallowance for pre-effective-date licence renewals, while payable includes paid su...
    Functional comparability requires data-driven analysis; outsourcing justified exclusion where no perversity undermined the Tribunal's factual findings...
    Limited scrutiny limits inquiries to notified issues, requiring deletion of an in-house R&D deduction disallowance beyond scope.
    Agricultural-land reinvestment qualifies when transfer consideration precedes replacement purchase, while unexamined claims may be reassessed on escap...
    Bona fide public fixed-deposit explanations prevent concealment penalties where unexplained-credit additions lack independent evidence of undisclosed ...
    Interest on excess refunds cannot be charged where reassessment follows an earlier scrutiny assessment rather than being the first assessment.
    Genuine political contributions require credible evidence beyond banking records; unsupported claims can lose deductions and penalty challenges remain...
    Misreporting penalty requires assessee-specific proof of accommodation-entry participation; donation deduction withdrawal alone cannot justify enhance...
    Safe-harbour tolerance for stamp-duty valuation applies retrospectively and prevents deemed income additions for marginal property-value differences.
    QCO exemption for steel imports applies when shipment met the cut-off and ARN was timely sought under SIMS.
    Statutory conclusion of customs proceedings bars later confiscation, redemption fine and penalty after timely payment of notified dues.
    Confiscation in rem survives, but customs penalties require proof that consignees knowingly participated in concealed imports.
    Tariff classification of anti-theft steering locks excludes the steering-system entry, defeating reclassification, confiscation, extended limitation, ...
    Alternative Customs Classification Claims Require Merits Review; Unavailable Goods Bar Redemption Fine and Bona Fide Claims Avoid Penalty.
❮
❯
❯❯
Maximize Maximize Maximize
0 / 200
Expand Note
Add to Folder

No Folders have been created

+

Are you sure you want to delete "My most important" ?

NOTE:

Highlights
Showing Results for :
Reset Filters
Results Found:
Show All Summaries Hide All Summaries

Highlights

Back

All Highlights

Showing Results for :
Reset Filters
No Records Found

Highlights

Back

All Highlights

Builder-financing additions for alleged cash receipts or...

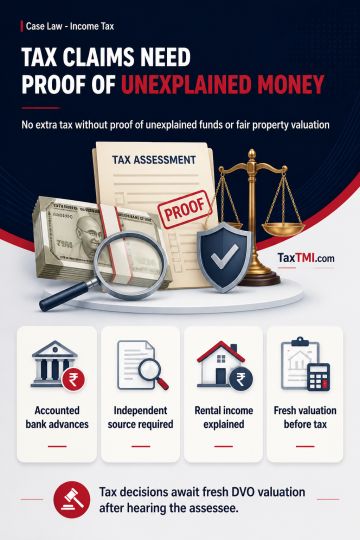
Builder-financing additions fail without proof of unexplained source, while disputed stamp values require DVO-based reassessment.

Contents
Summary
Note

Note

-

Bookmark

Print

Print

Income Tax October 9, 2026 Case Laws AT
Builder-financing additions for alleged cash receipts or payments cannot be sustained as unexplained money or unexplained investment where the amount represents return of an accounted banking-channel advance and no independent unexplained source or accretion is established. Alleged interest income cannot be inferred solely from a purported financing arrangement where property acquisitions were explained as investments generating rental income and capital gains. Stamp-duty valuation provisions apply to immovable-property acquisitions irrespective of their characterisation as builder financing. Where the stamp-duty value of under-construction property is disputed, fair market value must be determined through the statutory valuation mechanism before taxability and quantum are decided; the valuation issues require DVO-based fresh determination after hearing the assessee.

Topics

Acts Income Tax