Transfer-pricing comparability permits fresh objections and filters where software service comparables are functionally unsuitable for arm's-length pr...
Territorial rendering requirement excludes China-based management and consultancy services from fees for technical services under the India-China DTAA...
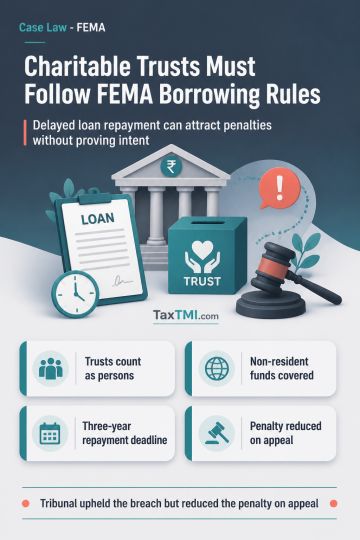
FEMA borrowing restrictions bind charitable trusts, and civil penalties apply without proving intent for delayed repayment of non-resident rupee loans...
Section 74 extended limitation under the CGST Act applies only where a tax shortfall, erroneous refund or wrongful input tax credit arose by reason of fraud, wilful misstatement or suppression of facts to evade tax. A show cause notice must plead foundational facts linking deliberate conduct to the alleged evasion; a mismatch, short payment, audit objection or mechanical use of statutory terms is insufficient. The proper officer must independently form the required satisfaction. Section 75 prevents an adjudicating order from adding grounds beyond the notice, so deficient fraud allegations cannot be cured later. Section 74 applies through Financial Year 2023-24, while Section 74A introduces a unified notice regime for later periods.
Section 74 extended limitation under the CGST Act applies only where a tax shortfall, erroneous refund or wrongful input tax credit arose by reason of fraud, wilful misstatement or suppression of facts to evade tax. A show cause notice must plead foundational facts linking deliberate conduct to the alleged evasion; a mismatch, short payment, audit objection or mechanical use of statutory terms is insufficient. The proper officer must independently form the required satisfaction. Section 75 prevents an adjudicating order from adding grounds beyond the notice, so deficient fraud allegations cannot be cured later. Section 74 applies through Financial Year 2023-24, while Section 74A introduces a unified notice regime for later periods.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4916