Call-recording requirements for institutional-investor client communications become non-mandatory, while institutional-investor status adopts the exis...
Restricted silver imports may clear under a valid import authorisation without additional status or exchange-routing requirements unless expressly imp...
Head Office cost allocation requires prescribed transfer-pricing methods; treaty ceilings bar surcharge and cess, while duplicate taxation is excluded...
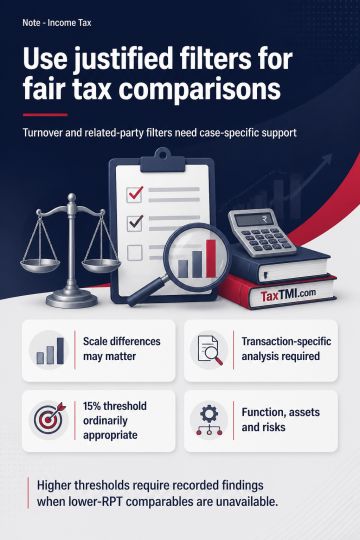
Transfer-pricing comparability under the transactional net margin method requires economically reliable uncontrolled benchmarks under Section 92C and Rule 10B. Turnover is not a standalone statutory bar, but material scale differences may justify excluding enterprises where brand value, intangibles, bargaining power, assets, risks or market conditions could affect margins. A turnover threshold must therefore be supported by transaction-specific comparability analysis rather than applied as a universal rule. Related-party transaction filters seek to reduce the influence of controlled dealings on comparable profitability. A 15% threshold is ordinarily appropriate where sufficient reliable comparables exist; a higher threshold requires a recorded finding that lower-RPT comparables are unavailable. Functional, asset and risk analysis remains essential, and appellate review may address disregard of statutory criteria or perverse findings.
Transfer-pricing comparability under the transactional net margin method requires economically reliable uncontrolled benchmarks under Section 92C and Rule 10B. Turnover is not a standalone statutory bar, but material scale differences may justify excluding enterprises where brand value, intangibles, bargaining power, assets, risks or market conditions could affect margins. A turnover threshold must therefore be supported by transaction-specific comparability analysis rather than applied as a universal rule. Related-party transaction filters seek to reduce the influence of controlled dealings on comparable profitability. A 15% threshold is ordinarily appropriate where sufficient reliable comparables exist; a higher threshold requires a recorded finding that lower-RPT comparables are unavailable. Functional, asset and risk analysis remains essential, and appellate review may address disregard of statutory criteria or perverse findings.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI