Constitutional personal-liberty safeguards limit PMLA twin bail conditions where completed investigations lead to prolonged incarceration before trial...
Automated airline software subscriptions without human intervention fail technical-services characterisation and do not make available underlying tech...
Business support recruitment and training receipts qualify for presumptive business taxation, not professional taxation under technical consultancy ru...
Treaty exemption for foreign permanent-establishment management fees prevailed, while dividend expense disallowance remained limited to an accepted al...
Centralised assessment transfers: participation after requesting centralisation can bar technical jurisdictional challenges, while assessment disputes...
Binding precedent remains operative despite pending challenge, supporting deletion of interest disallowance when debt is converted into preference sha...
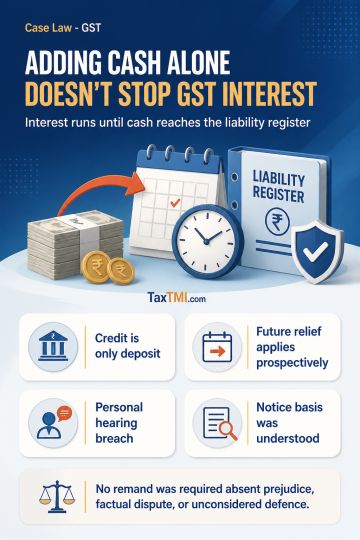
Interest on delayed GSTR-3B liabilities continues until the Electronic Cash Ledger is debited and the amount is credited to the electronic liability register; a cash-ledger credit alone is a deposit, not payment of an identified tax liability. The further proviso to Rule 88B(1), which excludes continuously available cash-ledger balances from interest computation, operates prospectively because it provides substantive relief without retrospective language. Failure to provide a requested personal hearing breaches Section 75(4), but does not require remand where no surviving prejudice, factual dispute, or unconsidered defence exists. A show-cause notice remains adequate where its basis was understood and fully answered without prejudice.
Interest on delayed GSTR-3B liabilities continues until the Electronic Cash Ledger is debited and the amount is credited to the electronic liability register; a cash-ledger credit alone is a deposit, not payment of an identified tax liability. The further proviso to Rule 88B(1), which excludes continuously available cash-ledger balances from interest computation, operates prospectively because it provides substantive relief without retrospective language. Failure to provide a requested personal hearing breaches Section 75(4), but does not require remand where no surviving prejudice, factual dispute, or unconsidered defence exists. A show-cause notice remains adequate where its basis was understood and fully answered without prejudice.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4910