Gross-profit additions on disputed purchases require reasoned appellate determination; disclosed claims alone do not support inaccurate-particulars pe...
Limitation after transfer-pricing remand: fresh TPO reference did not extend the assessment deadline, rendering the consequential assessment time-barr...
Interim judicial restraint on tax deduction prevents default, while supporting reasonable cause and penalty deletion for foreign-leg LFC reimbursement...
Palmolein classification defeated the crude-oil concession; material misdeclaration sustained recovery and confiscation, while separate false-document...
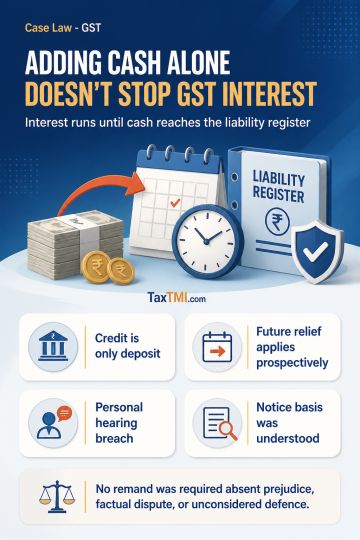
Interest on delayed GSTR-3B liabilities continues until the Electronic Cash Ledger is debited and the amount is credited to the electronic liability register; a cash-ledger credit alone is a deposit, not payment of an identified tax liability. The further proviso to Rule 88B(1), which excludes continuously available cash-ledger balances from interest computation, operates prospectively because it provides substantive relief without retrospective language. Failure to provide a requested personal hearing breaches Section 75(4), but does not require remand where no surviving prejudice, factual dispute, or unconsidered defence exists. A show-cause notice remains adequate where its basis was understood and fully answered without prejudice.
Interest on delayed GSTR-3B liabilities continues until the Electronic Cash Ledger is debited and the amount is credited to the electronic liability register; a cash-ledger credit alone is a deposit, not payment of an identified tax liability. The further proviso to Rule 88B(1), which excludes continuously available cash-ledger balances from interest computation, operates prospectively because it provides substantive relief without retrospective language. Failure to provide a requested personal hearing breaches Section 75(4), but does not require remand where no surviving prejudice, factual dispute, or unconsidered defence exists. A show-cause notice remains adequate where its basis was understood and fully answered without prejudice.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4907