Timely pronouncement of reserved judgments requires defined timelines, transparency measures, and remedial pathways to protect liberty and effective j...
Settlement-price depression requires proof of manipulation, not merely short exposure, late selling, or below-market orders, preserving disclosure pen...
Income Declaration Scheme declarations can evidence share-capital sources, while round-tripped funds and cash-linked credits require further verificat...
Page of 4908
Press 'Enter' after typing page number.
321 to 340 of 98141 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
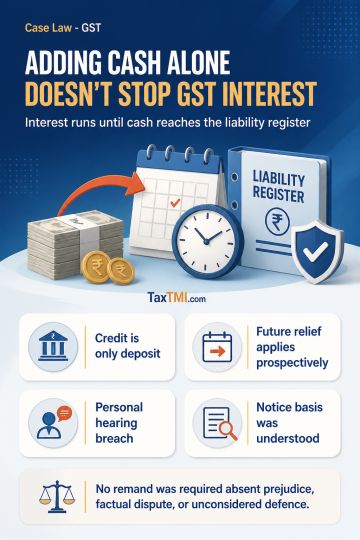
Interest on delayed GSTR-3B liabilities continues until the Electronic Cash Ledger is debited and the amount is credited to the electronic liability register; a cash-ledger credit alone is a deposit, not payment of an identified tax liability. The further proviso to Rule 88B(1), which excludes continuously available cash-ledger balances from interest computation, operates prospectively because it provides substantive relief without retrospective language. Failure to provide a requested personal hearing breaches Section 75(4), but does not require remand where no surviving prejudice, factual dispute, or unconsidered defence exists. A show-cause notice remains adequate where its basis was understood and fully answered without prejudice.
Interest on delayed GSTR-3B liabilities continues until the Electronic Cash Ledger is debited and the amount is credited to the electronic liability register; a cash-ledger credit alone is a deposit, not payment of an identified tax liability. The further proviso to Rule 88B(1), which excludes continuously available cash-ledger balances from interest computation, operates prospectively because it provides substantive relief without retrospective language. Failure to provide a requested personal hearing breaches Section 75(4), but does not require remand where no surviving prejudice, factual dispute, or unconsidered defence exists. A show-cause notice remains adequate where its basis was understood and fully answered without prejudice.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4908