Cost-to-cost reimbursement of seconded employees is not service consideration; transfer-pricing markup was deleted and amalgamation amortisation allow...
Crystallisation of liability supports prior-period expense deduction, while functionally distinct divisions require separate transfer-pricing benchmar...
Functional comparability under TNMM requires transaction-specific FAR analysis before benchmarking business-support services provided to associated en...
Advance pricing agreement methodology can guide benchmarking for non-covered years when functions, assets, risks and activities remain materially unch...
Tax-audit exemption for substantially State-funded educational universities prevents audit-failure penalties where income qualifies for statutory exem...
Functional, asset and risk analysis excludes diversified technology companies from captive software development comparables under cost-plus arrangemen...
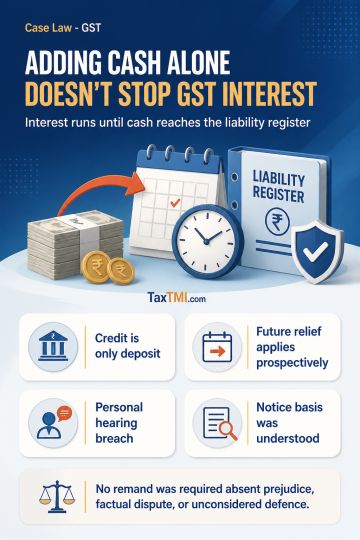
Interest on delayed GSTR-3B liabilities continues until the Electronic Cash Ledger is debited and the amount is credited to the electronic liability register; a cash-ledger credit alone is a deposit, not payment of an identified tax liability. The further proviso to Rule 88B(1), which excludes continuously available cash-ledger balances from interest computation, operates prospectively because it provides substantive relief without retrospective language. Failure to provide a requested personal hearing breaches Section 75(4), but does not require remand where no surviving prejudice, factual dispute, or unconsidered defence exists. A show-cause notice remains adequate where its basis was understood and fully answered without prejudice.
Interest on delayed GSTR-3B liabilities continues until the Electronic Cash Ledger is debited and the amount is credited to the electronic liability register; a cash-ledger credit alone is a deposit, not payment of an identified tax liability. The further proviso to Rule 88B(1), which excludes continuously available cash-ledger balances from interest computation, operates prospectively because it provides substantive relief without retrospective language. Failure to provide a requested personal hearing breaches Section 75(4), but does not require remand where no surviving prejudice, factual dispute, or unconsidered defence exists. A show-cause notice remains adequate where its basis was understood and fully answered without prejudice.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4913