Clubbing of income from gifted property failed where the claim surfaced after reassessment limitation, sustaining capital-gains assessment in spouse's...
Employee stock-option discount qualifies as revenue expenditure, while royalty and service comparables require reliable functional and transactional b...
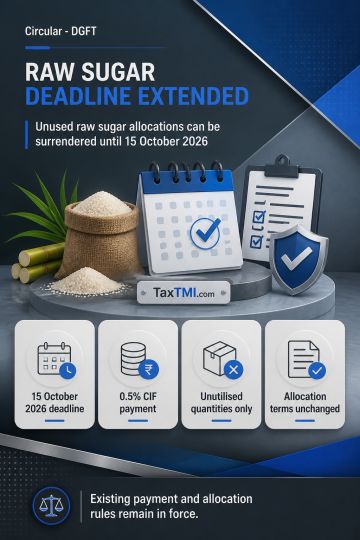
The deadline for TRQ holders to surrender unutilised quantities allocated for import of raw sugar is extended to 15 October 2026. Surrender remains subject to payment of 0.5% of the CIF value of the quantity surrendered, under the existing modalities. All other terms and conditions governing the tariff-rate quota allocation for raw sugar imports remain unchanged.
The deadline for TRQ holders to surrender unutilised quantities allocated for import of raw sugar is extended to 15 October 2026. Surrender remains subject to payment of 0.5% of the CIF value of the quantity surrendered, under the existing modalities. All other terms and conditions governing the tariff-rate quota allocation for raw sugar imports remain unchanged.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4912