Pharmaceutical transfer pricing can use profit splits based on manufacturing, intellectual property and marketing contributions rather than original v...
Inadvertent transfer pricing reporting omissions do not justify penalty where transactions were fully disclosed, benchmarked and accepted at arm's len...
Derivative trading loss disallowance requires transaction-specific evidence of manipulation once primary records discharge the taxpayer's initial burd...
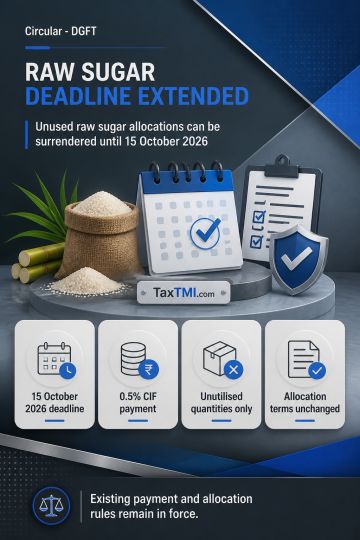
The deadline for TRQ holders to surrender unutilised quantities allocated for import of raw sugar is extended to 15 October 2026. Surrender remains subject to payment of 0.5% of the CIF value of the quantity surrendered, under the existing modalities. All other terms and conditions governing the tariff-rate quota allocation for raw sugar imports remain unchanged.
The deadline for TRQ holders to surrender unutilised quantities allocated for import of raw sugar is extended to 15 October 2026. Surrender remains subject to payment of 0.5% of the CIF value of the quantity surrendered, under the existing modalities. All other terms and conditions governing the tariff-rate quota allocation for raw sugar imports remain unchanged.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI


 Get Daily Updates