Timely pronouncement of reserved judgments requires defined timelines, transparency measures, and remedial pathways to protect liberty and effective j...
Settlement-price depression requires proof of manipulation, not merely short exposure, late selling, or below-market orders, preserving disclosure pen...
Income Declaration Scheme declarations can evidence share-capital sources, while round-tripped funds and cash-linked credits require further verificat...
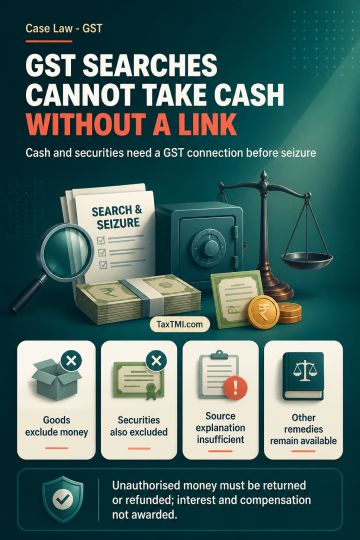
Section 67(2) of the CGST Act does not permit seizure of cash or securities merely because they are found during a GST search. Goods excludes money and securities, and the residuary expression "things" cannot be used to include items expressly excluded from goods. Cash being allegedly unaccounted, or an unsatisfactory explanation of its source, does not by itself establish the necessary nexus with GST proceedings. Money seized without authority must be returned or refunded. Interest and compensation for the unlawful seizure were not awarded, and other remedies remain available in law.
Section 67(2) of the CGST Act does not permit seizure of cash or securities merely because they are found during a GST search. Goods excludes money and securities, and the residuary expression "things" cannot be used to include items expressly excluded from goods. Cash being allegedly unaccounted, or an unsatisfactory explanation of its source, does not by itself establish the necessary nexus with GST proceedings. Money seized without authority must be returned or refunded. Interest and compensation for the unlawful seizure were not awarded, and other remedies remain available in law.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4912