PAN-level GST discrepancies require registration-specific evidence; withheld records and inferred suppression cannot establish liability without that ...
GST registration revocation requires payment of applicable ancillary dues, while admitted liabilities must be pursued through statutory recovery machi...
Steel processing and trading benchmarks require functional analysis, verified accounting data and attention to previously accepted transfer pricing me...
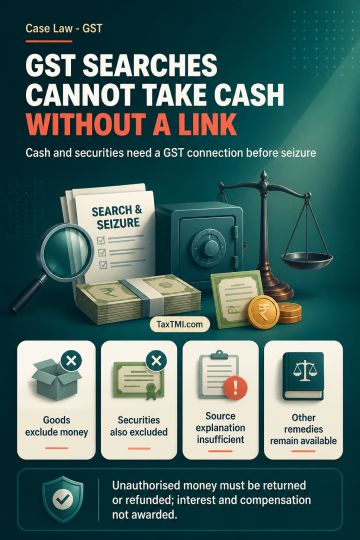
Section 67(2) of the CGST Act does not permit seizure of cash or securities merely because they are found during a GST search. Goods excludes money and securities, and the residuary expression "things" cannot be used to include items expressly excluded from goods. Cash being allegedly unaccounted, or an unsatisfactory explanation of its source, does not by itself establish the necessary nexus with GST proceedings. Money seized without authority must be returned or refunded. Interest and compensation for the unlawful seizure were not awarded, and other remedies remain available in law.
Section 67(2) of the CGST Act does not permit seizure of cash or securities merely because they are found during a GST search. Goods excludes money and securities, and the residuary expression "things" cannot be used to include items expressly excluded from goods. Cash being allegedly unaccounted, or an unsatisfactory explanation of its source, does not by itself establish the necessary nexus with GST proceedings. Money seized without authority must be returned or refunded. Interest and compensation for the unlawful seizure were not awarded, and other remedies remain available in law.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI


 Get Daily Updates