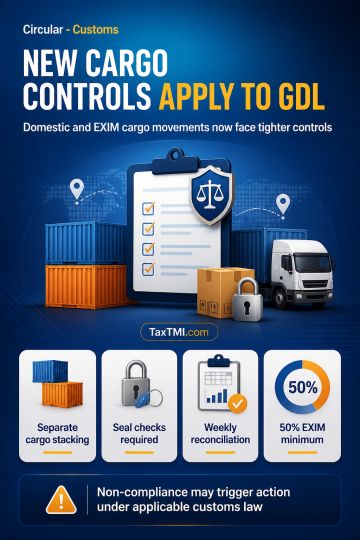
Customs-controlled cargo movement now includes GDL, subject to EXIM prioritisation, segregation, verification, reconciliation and enforcement safeguar...
GST cross-empowerment remains effective without conditional notification, while duplicate proceedings require established safeguards against overlappi...
Page of 4910
Press 'Enter' after typing page number.
641 to 660 of 98195 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
Pre-movement e-way bill compliance requires the e-way bill to be generated before goods begin moving, with the tax invoice and e-way bill carried by the person in charge. Generating those documents only after interception does not cure transportation undertaken without them. Their absence at interception creates a rebuttable presumption of intent to evade tax, which may be displaced only by a reasonable explanation. The explanation did not rebut that presumption, and the detention-related penalty under section 129 was sustained.
Pre-movement e-way bill compliance requires the e-way bill to be generated before goods begin moving, with the tax invoice and e-way bill carried by the person in charge. Generating those documents only after interception does not cure transportation undertaken without them. Their absence at interception creates a rebuttable presumption of intent to evade tax, which may be displaced only by a reasonable explanation. The explanation did not rebut that presumption, and the detention-related penalty under section 129 was sustained.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4910