PAN-level GST discrepancies require registration-specific evidence; withheld records and inferred suppression cannot establish liability without that ...
GST registration revocation requires payment of applicable ancillary dues, while admitted liabilities must be pursued through statutory recovery machi...
Steel processing and trading benchmarks require functional analysis, verified accounting data and attention to previously accepted transfer pricing me...
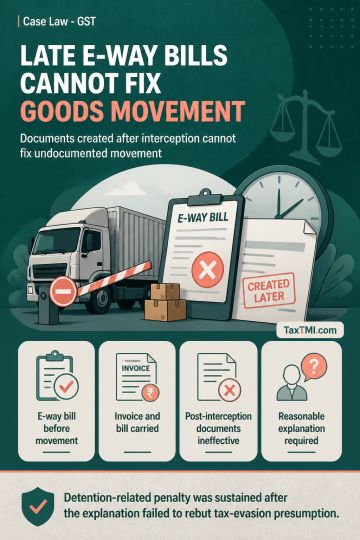
Pre-movement e-way bill compliance requires the e-way bill to be generated before goods begin moving, with the tax invoice and e-way bill carried by the person in charge. Generating those documents only after interception does not cure transportation undertaken without them. Their absence at interception creates a rebuttable presumption of intent to evade tax, which may be displaced only by a reasonable explanation. The explanation did not rebut that presumption, and the detention-related penalty under section 129 was sustained.
Pre-movement e-way bill compliance requires the e-way bill to be generated before goods begin moving, with the tax invoice and e-way bill carried by the person in charge. Generating those documents only after interception does not cure transportation undertaken without them. Their absence at interception creates a rebuttable presumption of intent to evade tax, which may be displaced only by a reasonable explanation. The explanation did not rebut that presumption, and the detention-related penalty under section 129 was sustained.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI


 Get Daily Updates