Suspension of insolvency professional registration prevents continued Resolution Professional appointments and restricts interim stays that effectivel...
Page of 4915
Press 'Enter' after typing page number.
341 to 360 of 98288 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
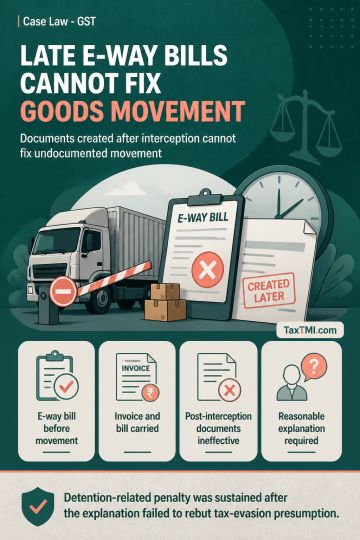
Pre-movement e-way bill compliance requires the e-way bill to be generated before goods begin moving, with the tax invoice and e-way bill carried by the person in charge. Generating those documents only after interception does not cure transportation undertaken without them. Their absence at interception creates a rebuttable presumption of intent to evade tax, which may be displaced only by a reasonable explanation. The explanation did not rebut that presumption, and the detention-related penalty under section 129 was sustained.
Pre-movement e-way bill compliance requires the e-way bill to be generated before goods begin moving, with the tax invoice and e-way bill carried by the person in charge. Generating those documents only after interception does not cure transportation undertaken without them. Their absence at interception creates a rebuttable presumption of intent to evade tax, which may be displaced only by a reasonable explanation. The explanation did not rebut that presumption, and the detention-related penalty under section 129 was sustained.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915