Cross-segment derivatives manipulation: integrated order patterns can support interim restraints, while director liability requires responsibility, co...
Power bank definition limits the customs-duty exclusion, preserving concessional treatment for stationary, grid-scale and industrial battery storage s...
Packing-material input credits support inverted-duty refunds for packaged tea, while rate-reduction and concessional-supply circulars remain inapplica...
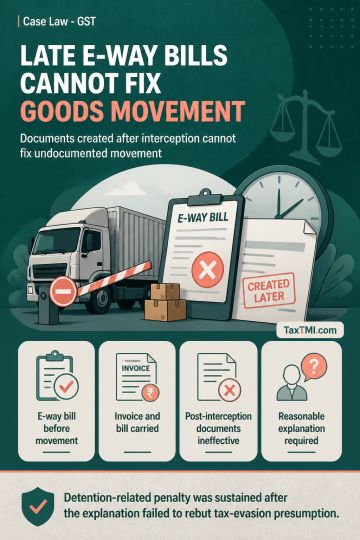
Pre-movement e-way bill compliance requires the e-way bill to be generated before goods begin moving, with the tax invoice and e-way bill carried by the person in charge. Generating those documents only after interception does not cure transportation undertaken without them. Their absence at interception creates a rebuttable presumption of intent to evade tax, which may be displaced only by a reasonable explanation. The explanation did not rebut that presumption, and the detention-related penalty under section 129 was sustained.
Pre-movement e-way bill compliance requires the e-way bill to be generated before goods begin moving, with the tax invoice and e-way bill carried by the person in charge. Generating those documents only after interception does not cure transportation undertaken without them. Their absence at interception creates a rebuttable presumption of intent to evade tax, which may be displaced only by a reasonable explanation. The explanation did not rebut that presumption, and the detention-related penalty under section 129 was sustained.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915