Capital-gains exemption for charitable trusts extends to qualifying fixed deposits, while unrecoverable TDS write-offs may constitute income applicati...
India-UK treaty characterisation of telecom-service receipts as business profits withstands unilateral domestic-law amendments for Indian tax purposes...
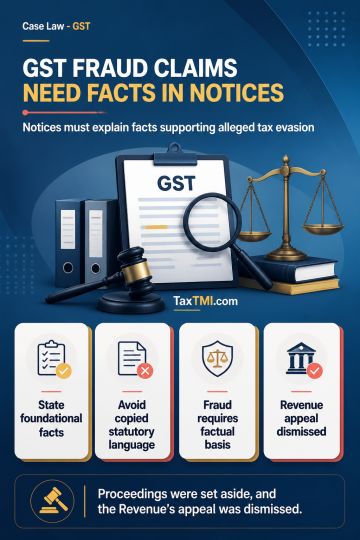
Section 74(1) may be invoked for delayed GST payment only where the show cause notice discloses foundational facts permitting an inference of fraud, wilful misstatement, or suppression with intent to evade tax. Mere mechanical reproduction of those statutory expressions does not satisfy that condition. Because the notice contained no such factual basis, recourse to section 74(1) was unwarranted; the Tribunal sustained the setting aside of the proceedings and dismissed the Revenue's appeal.
Section 74(1) may be invoked for delayed GST payment only where the show cause notice discloses foundational facts permitting an inference of fraud, wilful misstatement, or suppression with intent to evade tax. Mere mechanical reproduction of those statutory expressions does not satisfy that condition. Because the notice contained no such factual basis, recourse to section 74(1) was unwarranted; the Tribunal sustained the setting aside of the proceedings and dismissed the Revenue's appeal.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915