Pharmaceutical transfer pricing can use profit splits based on manufacturing, intellectual property and marketing contributions rather than original v...
Inadvertent transfer pricing reporting omissions do not justify penalty where transactions were fully disclosed, benchmarked and accepted at arm's len...
Derivative trading loss disallowance requires transaction-specific evidence of manipulation once primary records discharge the taxpayer's initial burd...
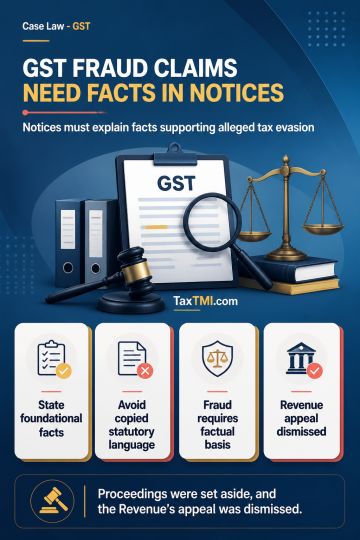
Section 74(1) may be invoked for delayed GST payment only where the show cause notice discloses foundational facts permitting an inference of fraud, wilful misstatement, or suppression with intent to evade tax. Mere mechanical reproduction of those statutory expressions does not satisfy that condition. Because the notice contained no such factual basis, recourse to section 74(1) was unwarranted; the Tribunal sustained the setting aside of the proceedings and dismissed the Revenue's appeal.
Section 74(1) may be invoked for delayed GST payment only where the show cause notice discloses foundational facts permitting an inference of fraud, wilful misstatement, or suppression with intent to evade tax. Mere mechanical reproduction of those statutory expressions does not satisfy that condition. Because the notice contained no such factual basis, recourse to section 74(1) was unwarranted; the Tribunal sustained the setting aside of the proceedings and dismissed the Revenue's appeal.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI


 Get Daily Updates