Customs-controlled cargo movement now includes GDL, subject to EXIM prioritisation, segregation, verification, reconciliation and enforcement safeguar...
GST cross-empowerment remains effective without conditional notification, while duplicate proceedings require established safeguards against overlappi...
Page of 4910
Press 'Enter' after typing page number.
641 to 660 of 98195 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
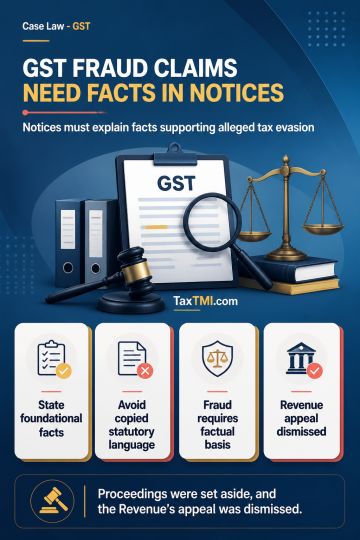
Section 74(1) may be invoked for delayed GST payment only where the show cause notice discloses foundational facts permitting an inference of fraud, wilful misstatement, or suppression with intent to evade tax. Mere mechanical reproduction of those statutory expressions does not satisfy that condition. Because the notice contained no such factual basis, recourse to section 74(1) was unwarranted; the Tribunal sustained the setting aside of the proceedings and dismissed the Revenue's appeal.
Section 74(1) may be invoked for delayed GST payment only where the show cause notice discloses foundational facts permitting an inference of fraud, wilful misstatement, or suppression with intent to evade tax. Mere mechanical reproduction of those statutory expressions does not satisfy that condition. Because the notice contained no such factual basis, recourse to section 74(1) was unwarranted; the Tribunal sustained the setting aside of the proceedings and dismissed the Revenue's appeal.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4910