Suspension of insolvency professional registration prevents continued Resolution Professional appointments and restricts interim stays that effectivel...
Page of 4915
Press 'Enter' after typing page number.
341 to 360 of 98288 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
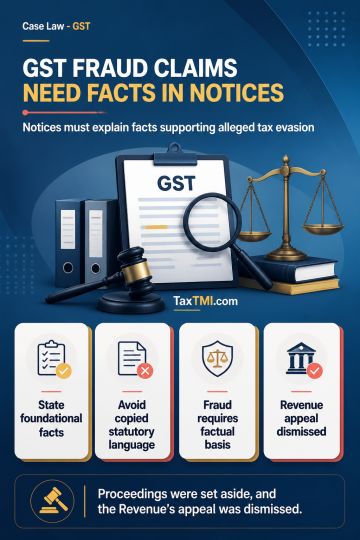
Section 74(1) may be invoked for delayed GST payment only where the show cause notice discloses foundational facts permitting an inference of fraud, wilful misstatement, or suppression with intent to evade tax. Mere mechanical reproduction of those statutory expressions does not satisfy that condition. Because the notice contained no such factual basis, recourse to section 74(1) was unwarranted; the Tribunal sustained the setting aside of the proceedings and dismissed the Revenue's appeal.
Section 74(1) may be invoked for delayed GST payment only where the show cause notice discloses foundational facts permitting an inference of fraud, wilful misstatement, or suppression with intent to evade tax. Mere mechanical reproduction of those statutory expressions does not satisfy that condition. Because the notice contained no such factual basis, recourse to section 74(1) was unwarranted; the Tribunal sustained the setting aside of the proceedings and dismissed the Revenue's appeal.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915