Customs-controlled cargo movement now includes GDL, subject to EXIM prioritisation, segregation, verification, reconciliation and enforcement safeguar...
GST cross-empowerment remains effective without conditional notification, while duplicate proceedings require established safeguards against overlappi...
Page of 4910
Press 'Enter' after typing page number.
641 to 660 of 98195 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
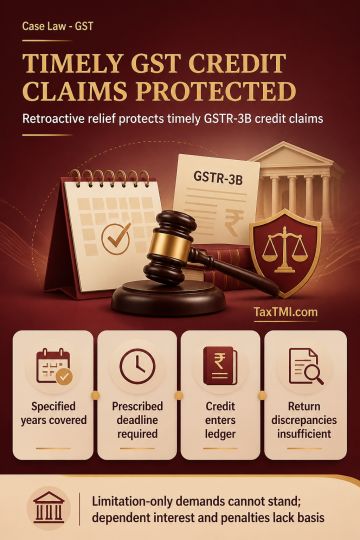
Retrospective section 16(5) permits input tax credit for specified financial years where claimed through GSTR-3B filed by the prescribed deadline, overriding the earlier limitation in section 16(4). GSTR-3B functions as the section 39 return for this purpose. Credit is availed when claimed and credited to the Electronic Credit Ledger; later utilisation does not constitute delayed availment. Discrepancies in GSTR-9 or GSTR-9C cannot by themselves extinguish credit already claimed through GSTR-3B. A demand founded solely on limitation cannot be sustained on new substantive grounds absent from the show-cause notice and original adjudication. Interest and penalty dependent exclusively on an invalid credit denial lack an independent basis.
Retrospective section 16(5) permits input tax credit for specified financial years where claimed through GSTR-3B filed by the prescribed deadline, overriding the earlier limitation in section 16(4). GSTR-3B functions as the section 39 return for this purpose. Credit is availed when claimed and credited to the Electronic Credit Ledger; later utilisation does not constitute delayed availment. Discrepancies in GSTR-9 or GSTR-9C cannot by themselves extinguish credit already claimed through GSTR-3B. A demand founded solely on limitation cannot be sustained on new substantive grounds absent from the show-cause notice and original adjudication. Interest and penalty dependent exclusively on an invalid credit denial lack an independent basis.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4910