Pharmaceutical transfer pricing can use profit splits based on manufacturing, intellectual property and marketing contributions rather than original v...
Inadvertent transfer pricing reporting omissions do not justify penalty where transactions were fully disclosed, benchmarked and accepted at arm's len...
Derivative trading loss disallowance requires transaction-specific evidence of manipulation once primary records discharge the taxpayer's initial burd...
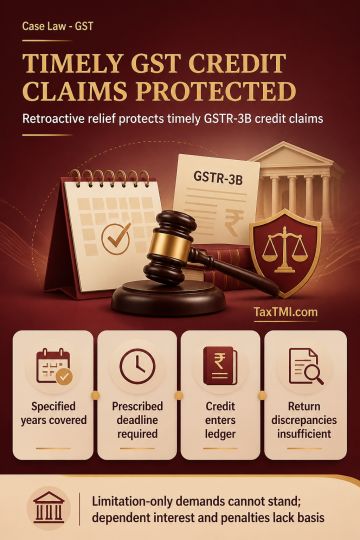
Retrospective section 16(5) permits input tax credit for specified financial years where claimed through GSTR-3B filed by the prescribed deadline, overriding the earlier limitation in section 16(4). GSTR-3B functions as the section 39 return for this purpose. Credit is availed when claimed and credited to the Electronic Credit Ledger; later utilisation does not constitute delayed availment. Discrepancies in GSTR-9 or GSTR-9C cannot by themselves extinguish credit already claimed through GSTR-3B. A demand founded solely on limitation cannot be sustained on new substantive grounds absent from the show-cause notice and original adjudication. Interest and penalty dependent exclusively on an invalid credit denial lack an independent basis.
Retrospective section 16(5) permits input tax credit for specified financial years where claimed through GSTR-3B filed by the prescribed deadline, overriding the earlier limitation in section 16(4). GSTR-3B functions as the section 39 return for this purpose. Credit is availed when claimed and credited to the Electronic Credit Ledger; later utilisation does not constitute delayed availment. Discrepancies in GSTR-9 or GSTR-9C cannot by themselves extinguish credit already claimed through GSTR-3B. A demand founded solely on limitation cannot be sustained on new substantive grounds absent from the show-cause notice and original adjudication. Interest and penalty dependent exclusively on an invalid credit denial lack an independent basis.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI


 Get Daily Updates