Capital-gains exemption for charitable trusts extends to qualifying fixed deposits, while unrecoverable TDS write-offs may constitute income applicati...
India-UK treaty characterisation of telecom-service receipts as business profits withstands unilateral domestic-law amendments for Indian tax purposes...
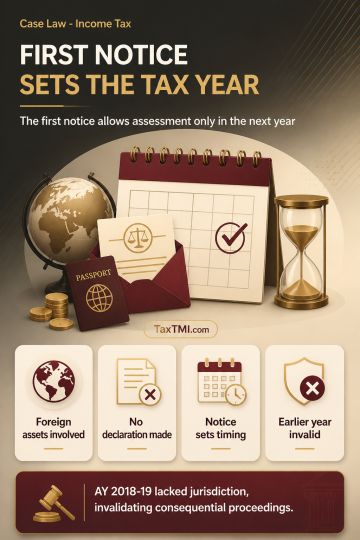
Section 72(c) of the Black Money Act creates a conclusive, self-executing fiction: undeclared foreign assets acquired before the Act commenced are deemed acquired in the previous year when a Section 10 notice is issued. Assessment must follow in the immediately succeeding assessment year. Where no declaration was made, Section 72(b) does not apply. A first notice in FY 2018-19 therefore permits assessment only for AY 2019-20, rendering assessment for AY 2018-19 without jurisdiction and invalidating consequential proceedings.
Section 72(c) of the Black Money Act creates a conclusive, self-executing fiction: undeclared foreign assets acquired before the Act commenced are deemed acquired in the previous year when a Section 10 notice is issued. Assessment must follow in the immediately succeeding assessment year. Where no declaration was made, Section 72(b) does not apply. A first notice in FY 2018-19 therefore permits assessment only for AY 2019-20, rendering assessment for AY 2018-19 without jurisdiction and invalidating consequential proceedings.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4916