Pharmaceutical transfer pricing can use profit splits based on manufacturing, intellectual property and marketing contributions rather than original v...
Inadvertent transfer pricing reporting omissions do not justify penalty where transactions were fully disclosed, benchmarked and accepted at arm's len...
Derivative trading loss disallowance requires transaction-specific evidence of manipulation once primary records discharge the taxpayer's initial burd...
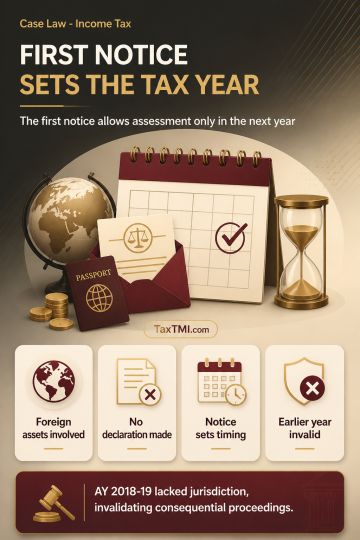
Section 72(c) of the Black Money Act creates a conclusive, self-executing fiction: undeclared foreign assets acquired before the Act commenced are deemed acquired in the previous year when a Section 10 notice is issued. Assessment must follow in the immediately succeeding assessment year. Where no declaration was made, Section 72(b) does not apply. A first notice in FY 2018-19 therefore permits assessment only for AY 2019-20, rendering assessment for AY 2018-19 without jurisdiction and invalidating consequential proceedings.
Section 72(c) of the Black Money Act creates a conclusive, self-executing fiction: undeclared foreign assets acquired before the Act commenced are deemed acquired in the previous year when a Section 10 notice is issued. Assessment must follow in the immediately succeeding assessment year. Where no declaration was made, Section 72(b) does not apply. A first notice in FY 2018-19 therefore permits assessment only for AY 2019-20, rendering assessment for AY 2018-19 without jurisdiction and invalidating consequential proceedings.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI


 Get Daily Updates