Anti-profiteering obligations survive business demerger, complaint withdrawal, and customized supply arrangements where rate-reduction benefits are no...
Road restoration charges constitute taxable services when requested for commercial pipeline activity, requiring reverse-charge GST from the business r...
Interest on delayed release of requisitioned cash includes statutory pre-assessment interest and restitutionary compensation for unlawful post-assessm...
Incomplete inventory records justify rejecting accounts, while profit estimation requires relevant comparable material and interest falls under other ...
Transfer-pricing comparability requires functional alignment; delayed associated-enterprise receivables need separate LIBOR-based benchmarking, while ...
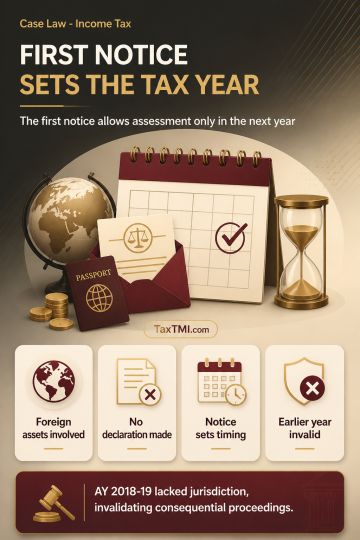
Section 72(c) of the Black Money Act creates a conclusive, self-executing fiction: undeclared foreign assets acquired before the Act commenced are deemed acquired in the previous year when a Section 10 notice is issued. Assessment must follow in the immediately succeeding assessment year. Where no declaration was made, Section 72(b) does not apply. A first notice in FY 2018-19 therefore permits assessment only for AY 2019-20, rendering assessment for AY 2018-19 without jurisdiction and invalidating consequential proceedings.
Section 72(c) of the Black Money Act creates a conclusive, self-executing fiction: undeclared foreign assets acquired before the Act commenced are deemed acquired in the previous year when a Section 10 notice is issued. Assessment must follow in the immediately succeeding assessment year. Where no declaration was made, Section 72(b) does not apply. A first notice in FY 2018-19 therefore permits assessment only for AY 2019-20, rendering assessment for AY 2018-19 without jurisdiction and invalidating consequential proceedings.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4912