Faceless assessment safeguards require requested personal hearings and adequate final show-cause response time, failing which reassessment is required...
Embezzlement losses in charitable institutions remain allowable when misappropriation is established, irrecoverable, and not a specified-person benefi...
National long-distance undertaking status supports deduction where separately licensed infrastructure, resources, revenue, and expenditure establish c...
Agency reimbursement income follows contractual deposit-liability computation, while pending deposit collections do not constitute deemed-dividend loa...
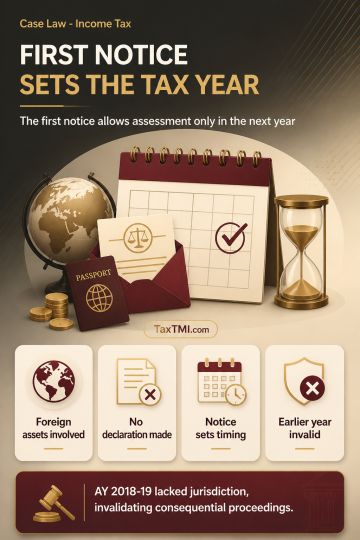
Section 72(c) of the Black Money Act creates a conclusive, self-executing fiction: undeclared foreign assets acquired before the Act commenced are deemed acquired in the previous year when a Section 10 notice is issued. Assessment must follow in the immediately succeeding assessment year. Where no declaration was made, Section 72(b) does not apply. A first notice in FY 2018-19 therefore permits assessment only for AY 2019-20, rendering assessment for AY 2018-19 without jurisdiction and invalidating consequential proceedings.
Section 72(c) of the Black Money Act creates a conclusive, self-executing fiction: undeclared foreign assets acquired before the Act commenced are deemed acquired in the previous year when a Section 10 notice is issued. Assessment must follow in the immediately succeeding assessment year. Where no declaration was made, Section 72(b) does not apply. A first notice in FY 2018-19 therefore permits assessment only for AY 2019-20, rendering assessment for AY 2018-19 without jurisdiction and invalidating consequential proceedings.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4908