Compulsorily convertible debentures remain debt before conversion, preventing transfer-pricing and interest-deduction disallowances on the stated fact...
Stock-in-trade transfer taxability follows possession and consideration, not later conveyance registration, limiting deemed-value provisions to the ac...
Alternative statutory remedy under GST bars writ challenge where classification, notice variance, and hearing disputes require factual appellate revie...
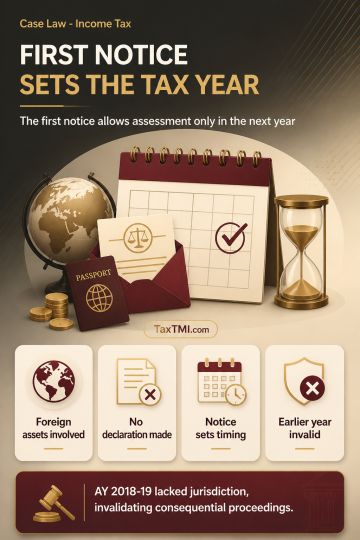
Section 72(c) of the Black Money Act creates a conclusive, self-executing fiction: undeclared foreign assets acquired before the Act commenced are deemed acquired in the previous year when a Section 10 notice is issued. Assessment must follow in the immediately succeeding assessment year. Where no declaration was made, Section 72(b) does not apply. A first notice in FY 2018-19 therefore permits assessment only for AY 2019-20, rendering assessment for AY 2018-19 without jurisdiction and invalidating consequential proceedings.
Section 72(c) of the Black Money Act creates a conclusive, self-executing fiction: undeclared foreign assets acquired before the Act commenced are deemed acquired in the previous year when a Section 10 notice is issued. Assessment must follow in the immediately succeeding assessment year. Where no declaration was made, Section 72(b) does not apply. A first notice in FY 2018-19 therefore permits assessment only for AY 2019-20, rendering assessment for AY 2018-19 without jurisdiction and invalidating consequential proceedings.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4910