Constitutional personal-liberty safeguards limit PMLA twin bail conditions where completed investigations lead to prolonged incarceration before trial...
Automated airline software subscriptions without human intervention fail technical-services characterisation and do not make available underlying tech...
Business support recruitment and training receipts qualify for presumptive business taxation, not professional taxation under technical consultancy ru...
Treaty exemption for foreign permanent-establishment management fees prevailed, while dividend expense disallowance remained limited to an accepted al...
Centralised assessment transfers: participation after requesting centralisation can bar technical jurisdictional challenges, while assessment disputes...
Binding precedent remains operative despite pending challenge, supporting deletion of interest disallowance when debt is converted into preference sha...
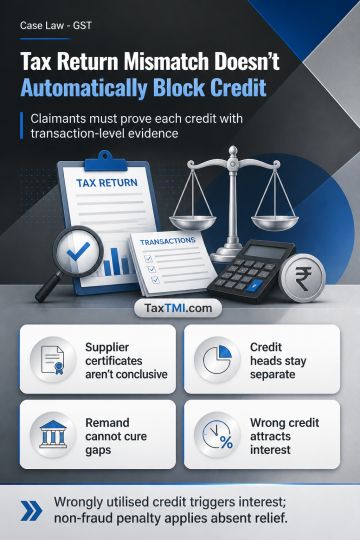
GSTR-2A non-reflection for FY 2018-19 operates as a scrutiny trigger rather than an automatic bar to input tax credit, but the claimant must prove substantive eligibility with objective, transaction-level evidence. A supplier certificate is evidentiary material, not a statutory deeming rule; unsupported B2C-reporting errors and residual IGST mismatches do not establish credit. IGST, CGST and SGST are distinct credit heads, so cross-head set-off requires legally permissible, transaction-level reconciliation. Additional evidence cannot fill evidentiary gaps or justify remand after adequate opportunities. Where wrongly availed credit was utilised, interest follows absent a demonstrated computational error, and non-fraud penalty applies where no separate basis for relief exists.
GSTR-2A non-reflection for FY 2018-19 operates as a scrutiny trigger rather than an automatic bar to input tax credit, but the claimant must prove substantive eligibility with objective, transaction-level evidence. A supplier certificate is evidentiary material, not a statutory deeming rule; unsupported B2C-reporting errors and residual IGST mismatches do not establish credit. IGST, CGST and SGST are distinct credit heads, so cross-head set-off requires legally permissible, transaction-level reconciliation. Additional evidence cannot fill evidentiary gaps or justify remand after adequate opportunities. Where wrongly availed credit was utilised, interest follows absent a demonstrated computational error, and non-fraud penalty applies where no separate basis for relief exists.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4910