SEZ-unit profit deduction covers voluntary transfer-pricing adjustments, while exempt-income costs, foreign-exchange loss and ITeS comparables are exa...
Infrastructure-development deduction remains available to EPC contractors when substantive statutory conditions outweigh contractor labels in agreemen...
Page of 4910
Press 'Enter' after typing page number.
761 to 780 of 98196 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
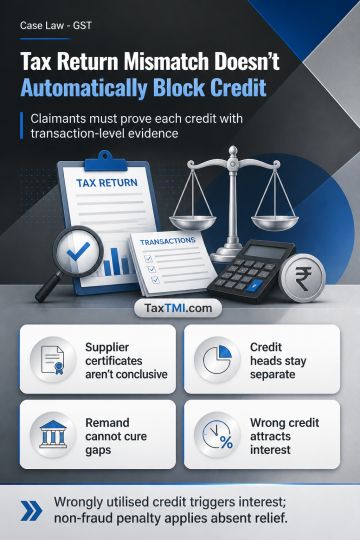
GSTR-2A non-reflection for FY 2018-19 operates as a scrutiny trigger rather than an automatic bar to input tax credit, but the claimant must prove substantive eligibility with objective, transaction-level evidence. A supplier certificate is evidentiary material, not a statutory deeming rule; unsupported B2C-reporting errors and residual IGST mismatches do not establish credit. IGST, CGST and SGST are distinct credit heads, so cross-head set-off requires legally permissible, transaction-level reconciliation. Additional evidence cannot fill evidentiary gaps or justify remand after adequate opportunities. Where wrongly availed credit was utilised, interest follows absent a demonstrated computational error, and non-fraud penalty applies where no separate basis for relief exists.
GSTR-2A non-reflection for FY 2018-19 operates as a scrutiny trigger rather than an automatic bar to input tax credit, but the claimant must prove substantive eligibility with objective, transaction-level evidence. A supplier certificate is evidentiary material, not a statutory deeming rule; unsupported B2C-reporting errors and residual IGST mismatches do not establish credit. IGST, CGST and SGST are distinct credit heads, so cross-head set-off requires legally permissible, transaction-level reconciliation. Additional evidence cannot fill evidentiary gaps or justify remand after adequate opportunities. Where wrongly availed credit was utilised, interest follows absent a demonstrated computational error, and non-fraud penalty applies where no separate basis for relief exists.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4910