Supervisory permanent establishment requires project-wise duration and qualifying construction nexus; offshore supplies and salary reimbursements rema...
Transfer-pricing comparability permits fresh objections and filters where software service comparables are functionally unsuitable for arm's-length pr...
Territorial rendering requirement excludes China-based management and consultancy services from fees for technical services under the India-China DTAA...
Page of 4910
Press 'Enter' after typing page number.
721 to 740 of 98195 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
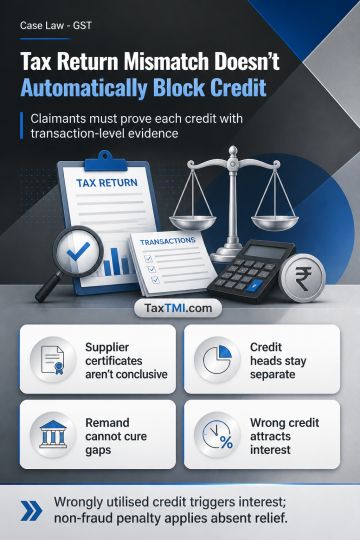
GSTR-2A non-reflection for FY 2018-19 operates as a scrutiny trigger rather than an automatic bar to input tax credit, but the claimant must prove substantive eligibility with objective, transaction-level evidence. A supplier certificate is evidentiary material, not a statutory deeming rule; unsupported B2C-reporting errors and residual IGST mismatches do not establish credit. IGST, CGST and SGST are distinct credit heads, so cross-head set-off requires legally permissible, transaction-level reconciliation. Additional evidence cannot fill evidentiary gaps or justify remand after adequate opportunities. Where wrongly availed credit was utilised, interest follows absent a demonstrated computational error, and non-fraud penalty applies where no separate basis for relief exists.
GSTR-2A non-reflection for FY 2018-19 operates as a scrutiny trigger rather than an automatic bar to input tax credit, but the claimant must prove substantive eligibility with objective, transaction-level evidence. A supplier certificate is evidentiary material, not a statutory deeming rule; unsupported B2C-reporting errors and residual IGST mismatches do not establish credit. IGST, CGST and SGST are distinct credit heads, so cross-head set-off requires legally permissible, transaction-level reconciliation. Additional evidence cannot fill evidentiary gaps or justify remand after adequate opportunities. Where wrongly availed credit was utilised, interest follows absent a demonstrated computational error, and non-fraud penalty applies where no separate basis for relief exists.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4910