Scientific research association approval requires continuing SIRO status, annual donation reporting, and donor certificates for the approved foundatio...
Scientific research institution approval is conditional on SIRO recognition, annual donation reporting, donor certification, and prescribed compliance...
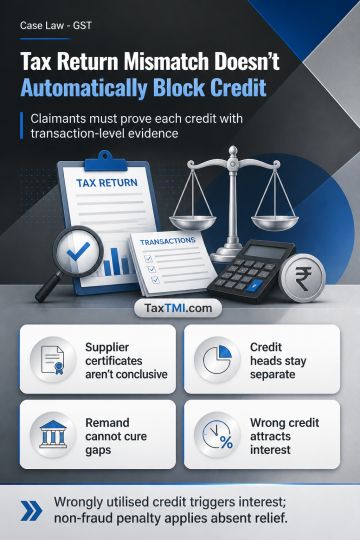
GSTR-2A non-reflection for FY 2018-19 operates as a scrutiny trigger rather than an automatic bar to input tax credit, but the claimant must prove substantive eligibility with objective, transaction-level evidence. A supplier certificate is evidentiary material, not a statutory deeming rule; unsupported B2C-reporting errors and residual IGST mismatches do not establish credit. IGST, CGST and SGST are distinct credit heads, so cross-head set-off requires legally permissible, transaction-level reconciliation. Additional evidence cannot fill evidentiary gaps or justify remand after adequate opportunities. Where wrongly availed credit was utilised, interest follows absent a demonstrated computational error, and non-fraud penalty applies where no separate basis for relief exists.
GSTR-2A non-reflection for FY 2018-19 operates as a scrutiny trigger rather than an automatic bar to input tax credit, but the claimant must prove substantive eligibility with objective, transaction-level evidence. A supplier certificate is evidentiary material, not a statutory deeming rule; unsupported B2C-reporting errors and residual IGST mismatches do not establish credit. IGST, CGST and SGST are distinct credit heads, so cross-head set-off requires legally permissible, transaction-level reconciliation. Additional evidence cannot fill evidentiary gaps or justify remand after adequate opportunities. Where wrongly availed credit was utilised, interest follows absent a demonstrated computational error, and non-fraud penalty applies where no separate basis for relief exists.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4907