Embezzlement losses in charitable institutions remain allowable when misappropriation is established, irrecoverable, and not a specified-person benefi...
National long-distance undertaking status supports deduction where separately licensed infrastructure, resources, revenue, and expenditure establish c...
Agency reimbursement income follows contractual deposit-liability computation, while pending deposit collections do not constitute deemed-dividend loa...
Membership-consent thresholds for oppression petitions are satisfied by unchallenged voter-list consents, while unsupported forgery claims require pro...
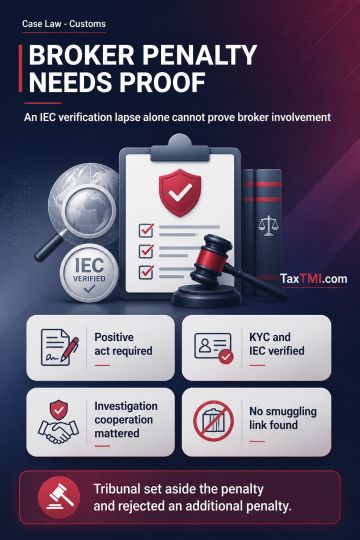
Penal liability of a Customs Broker for abetment of attempted Red Sanders export requires evidence of a positive act, prior knowledge, active collusion, or assistance; failure alone to verify an IEC holder does not establish abetment. Where the Broker obtained and verified KYC and IEC documents, co-operated with the investigation, and no evidence linked it to the attempted smuggling, the Tribunal found no basis for an abetment penalty. The penalty was set aside, and the Revenue's attempt to impose an additional penalty was rejected.
Penal liability of a Customs Broker for abetment of attempted Red Sanders export requires evidence of a positive act, prior knowledge, active collusion, or assistance; failure alone to verify an IEC holder does not establish abetment. Where the Broker obtained and verified KYC and IEC documents, co-operated with the investigation, and no evidence linked it to the attempted smuggling, the Tribunal found no basis for an abetment penalty. The penalty was set aside, and the Revenue's attempt to impose an additional penalty was rejected.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4910