Blocked input tax credit for resort construction remains unavailable; interest follows actual utilisation, while delayed payment attracts statutory pe...
Duplicate PAN allocation requires record verification and deactivation reasons before assessment-related transactions can be attributed to an assessee...
Faceless assessment safeguards require requested personal hearings and adequate final show-cause response time, failing which reassessment is required...
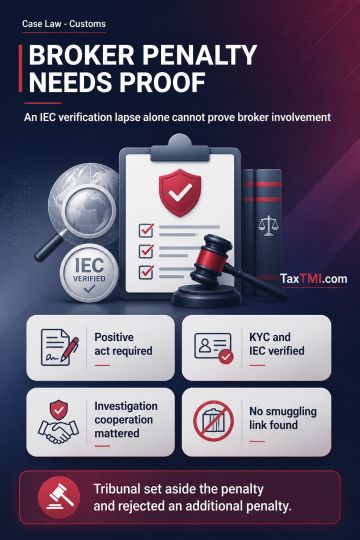
Penal liability of a Customs Broker for abetment of attempted Red Sanders export requires evidence of a positive act, prior knowledge, active collusion, or assistance; failure alone to verify an IEC holder does not establish abetment. Where the Broker obtained and verified KYC and IEC documents, co-operated with the investigation, and no evidence linked it to the attempted smuggling, the Tribunal found no basis for an abetment penalty. The penalty was set aside, and the Revenue's attempt to impose an additional penalty was rejected.
Penal liability of a Customs Broker for abetment of attempted Red Sanders export requires evidence of a positive act, prior knowledge, active collusion, or assistance; failure alone to verify an IEC holder does not establish abetment. Where the Broker obtained and verified KYC and IEC documents, co-operated with the investigation, and no evidence linked it to the attempted smuggling, the Tribunal found no basis for an abetment penalty. The penalty was set aside, and the Revenue's attempt to impose an additional penalty was rejected.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4910