Capital-gains exemption for charitable trusts extends to qualifying fixed deposits, while unrecoverable TDS write-offs may constitute income applicati...
India-UK treaty characterisation of telecom-service receipts as business profits withstands unilateral domestic-law amendments for Indian tax purposes...
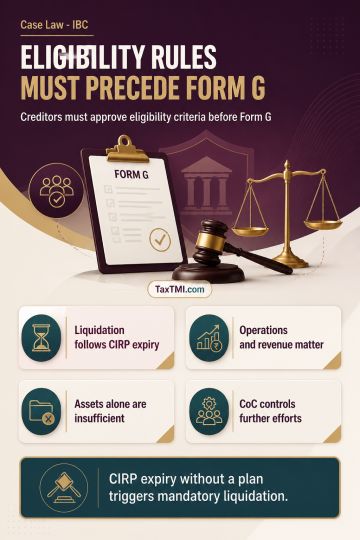
Prior Committee of Creditors approval of eligibility criteria is required before publication of Form G; Regulation 36A's publication timeline does not displace that requirement. On expiry of the CIRP without receipt of a resolution plan, section 33(1)(a) mandates liquidation, and a pending application alleging fraudulent or malicious initiation does not automatically halt that consequence. Going-concern status requires ongoing business operations, personnel and revenue generation, rather than residual assets alone. A suspended board has no unconditional right to impleadment in liquidation proceedings governed by objective statutory conditions. Further resolution efforts remain within the CoC's commercial judgment, which appellate review cannot replace.
Prior Committee of Creditors approval of eligibility criteria is required before publication of Form G; Regulation 36A's publication timeline does not displace that requirement. On expiry of the CIRP without receipt of a resolution plan, section 33(1)(a) mandates liquidation, and a pending application alleging fraudulent or malicious initiation does not automatically halt that consequence. Going-concern status requires ongoing business operations, personnel and revenue generation, rather than residual assets alone. A suspended board has no unconditional right to impleadment in liquidation proceedings governed by objective statutory conditions. Further resolution efforts remain within the CoC's commercial judgment, which appellate review cannot replace.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4912