SEZ-unit profit deduction covers voluntary transfer-pricing adjustments, while exempt-income costs, foreign-exchange loss and ITeS comparables are exa...
Infrastructure-development deduction remains available to EPC contractors when substantive statutory conditions outweigh contractor labels in agreemen...
Page of 4910
Press 'Enter' after typing page number.
761 to 780 of 98196 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
Under FEMA, a charitable trust is an artificial juridical person...
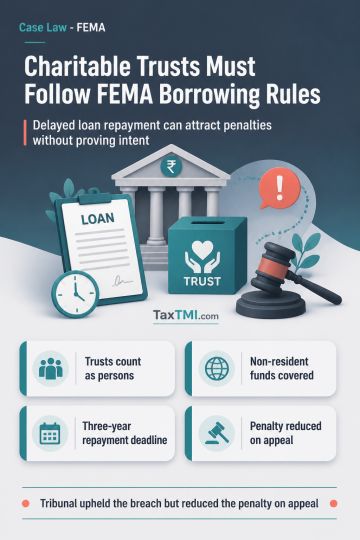
FEMA borrowing restrictions bind charitable trusts, and civil penalties apply without proving intent for delayed repayment of non-resident rupee loans.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Under FEMA, a charitable trust is an artificial juridical person within the inclusive definition of "person"; funds received from non-resident trustees and recorded as borrowings remain subject to FEMA regardless of charitable purpose. Omission of section 6(3) did not invalidate proceedings commenced before the omission took effect. Non-repatriable rupee loans from non-resident Indians had to be repaid within three years, including through credit to NRO or NRSR accounts. Contravention is a civil breach attracting penalty without proof of mens rea under section 13(1). The Tribunal upheld the breach but reduced the penalty on appeal.
Under FEMA, a charitable trust is an artificial juridical person within the inclusive definition of "person"; funds received from non-resident trustees and recorded as borrowings remain subject to FEMA regardless of charitable purpose. Omission of section 6(3) did not invalidate proceedings commenced before the omission took effect. Non-repatriable rupee loans from non-resident Indians had to be repaid within three years, including through credit to NRO or NRSR accounts. Contravention is a civil breach attracting penalty without proof of mens rea under section 13(1). The Tribunal upheld the breach but reduced the penalty on appeal.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4910