Income Declaration Scheme declarations can evidence share-capital sources, while round-tripped funds and cash-linked credits require further verificat...
Permanent establishment tests: independent subsidiary premises and principal-to-principal dealings did not create Indian taxability for offshore suppl...
Valuation Officer estimates govern property-value additions once statutory valuation is invoked, requiring fresh consideration of objections and compa...
Waiver of written show-cause notice may prevent a later procedural challenge after participation in customs adjudication, preserving statutory appella...
Under FEMA, a charitable trust is an artificial juridical person...
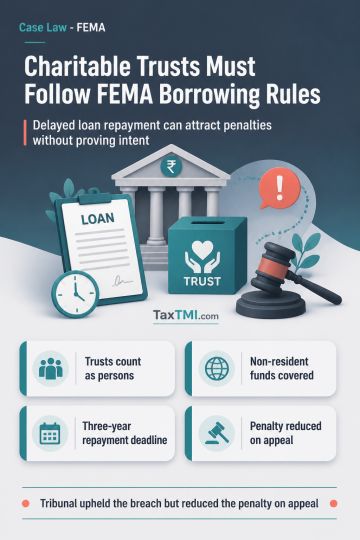
FEMA borrowing restrictions bind charitable trusts, and civil penalties apply without proving intent for delayed repayment of non-resident rupee loans.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Under FEMA, a charitable trust is an artificial juridical person within the inclusive definition of "person"; funds received from non-resident trustees and recorded as borrowings remain subject to FEMA regardless of charitable purpose. Omission of section 6(3) did not invalidate proceedings commenced before the omission took effect. Non-repatriable rupee loans from non-resident Indians had to be repaid within three years, including through credit to NRO or NRSR accounts. Contravention is a civil breach attracting penalty without proof of mens rea under section 13(1). The Tribunal upheld the breach but reduced the penalty on appeal.
Under FEMA, a charitable trust is an artificial juridical person within the inclusive definition of "person"; funds received from non-resident trustees and recorded as borrowings remain subject to FEMA regardless of charitable purpose. Omission of section 6(3) did not invalidate proceedings commenced before the omission took effect. Non-repatriable rupee loans from non-resident Indians had to be repaid within three years, including through credit to NRO or NRSR accounts. Contravention is a civil breach attracting penalty without proof of mens rea under section 13(1). The Tribunal upheld the breach but reduced the penalty on appeal.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4913