Road restoration charges constitute taxable services when requested for commercial pipeline activity, requiring reverse-charge GST from the business r...
Interest on delayed release of requisitioned cash includes statutory pre-assessment interest and restitutionary compensation for unlawful post-assessm...
Incomplete inventory records justify rejecting accounts, while profit estimation requires relevant comparable material and interest falls under other ...
Transfer-pricing comparability requires functional alignment; delayed associated-enterprise receivables need separate LIBOR-based benchmarking, while ...
Extended reassessment limitation in search cases requires asset-linked escaped income, invalidating additions based only on unexplained money or expen...
Enhanced tolerance band under section 43CA applies retrospectively, deleting qualifying deemed-sale additions while disputed stamp valuation requires ...
Under FEMA, a charitable trust is an artificial juridical person...
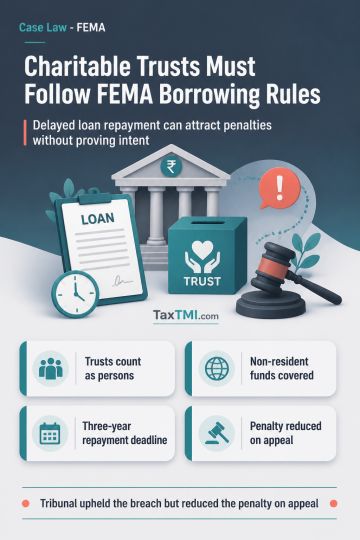
FEMA borrowing restrictions bind charitable trusts, and civil penalties apply without proving intent for delayed repayment of non-resident rupee loans.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Under FEMA, a charitable trust is an artificial juridical person within the inclusive definition of "person"; funds received from non-resident trustees and recorded as borrowings remain subject to FEMA regardless of charitable purpose. Omission of section 6(3) did not invalidate proceedings commenced before the omission took effect. Non-repatriable rupee loans from non-resident Indians had to be repaid within three years, including through credit to NRO or NRSR accounts. Contravention is a civil breach attracting penalty without proof of mens rea under section 13(1). The Tribunal upheld the breach but reduced the penalty on appeal.
Under FEMA, a charitable trust is an artificial juridical person within the inclusive definition of "person"; funds received from non-resident trustees and recorded as borrowings remain subject to FEMA regardless of charitable purpose. Omission of section 6(3) did not invalidate proceedings commenced before the omission took effect. Non-repatriable rupee loans from non-resident Indians had to be repaid within three years, including through credit to NRO or NRSR accounts. Contravention is a civil breach attracting penalty without proof of mens rea under section 13(1). The Tribunal upheld the breach but reduced the penalty on appeal.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4910