Tax-audit exemption for substantially State-funded educational universities prevents audit-failure penalties where income qualifies for statutory exem...
Functional, asset and risk analysis excludes diversified technology companies from captive software development comparables under cost-plus arrangemen...
Mobile-phone electronic evidence failed to establish customs undervaluation, while duty survived on non-authentic origin certificates without importer...
Automotive radio classification treats integrated infotainment features as supplementary, placing complete and qualifying unassembled units under the ...
Separate corporate personality prevents directors from being personally liable for company deposits without a guarantee or independent legal undertaki...
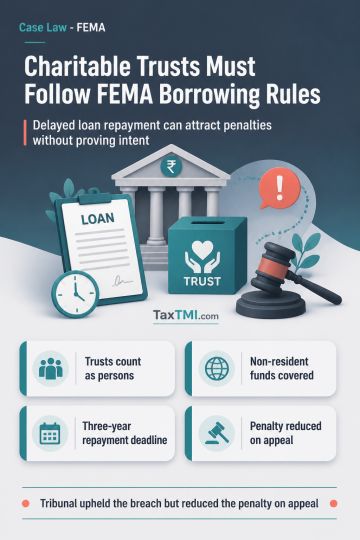
Under FEMA, a charitable trust is an artificial juridical person...
FEMA borrowing restrictions bind charitable trusts, and civil penalties apply without proving intent for delayed repayment of non-resident rupee loans.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Under FEMA, a charitable trust is an artificial juridical person within the inclusive definition of "person"; funds received from non-resident trustees and recorded as borrowings remain subject to FEMA regardless of charitable purpose. Omission of section 6(3) did not invalidate proceedings commenced before the omission took effect. Non-repatriable rupee loans from non-resident Indians had to be repaid within three years, including through credit to NRO or NRSR accounts. Contravention is a civil breach attracting penalty without proof of mens rea under section 13(1). The Tribunal upheld the breach but reduced the penalty on appeal.
Under FEMA, a charitable trust is an artificial juridical person within the inclusive definition of "person"; funds received from non-resident trustees and recorded as borrowings remain subject to FEMA regardless of charitable purpose. Omission of section 6(3) did not invalidate proceedings commenced before the omission took effect. Non-repatriable rupee loans from non-resident Indians had to be repaid within three years, including through credit to NRO or NRSR accounts. Contravention is a civil breach attracting penalty without proof of mens rea under section 13(1). The Tribunal upheld the breach but reduced the penalty on appeal.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4912