Head Office cost allocation requires prescribed transfer-pricing methods; treaty ceilings bar surcharge and cess, while duplicate taxation is excluded...
Cost-to-cost reimbursement of seconded employees is not service consideration; transfer-pricing markup was deleted and amalgamation amortisation allow...
Crystallisation of liability supports prior-period expense deduction, while functionally distinct divisions require separate transfer-pricing benchmar...
Functional comparability under TNMM requires transaction-specific FAR analysis before benchmarking business-support services provided to associated en...
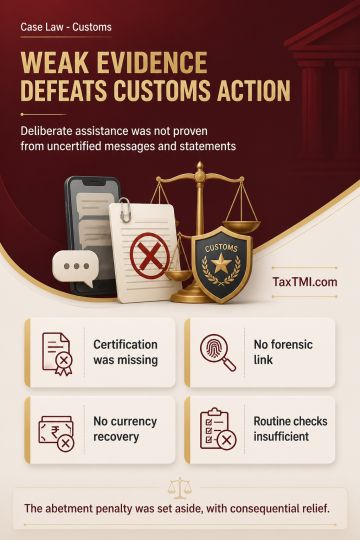
Electronic records relied on in customs penalty proceedings require prescribed certification, and an uncertified text-message printout has no evidentiary value where no forensic material links it to the alleged user. Such material cannot implicate a Customs officer in attempted illegal export of foreign currency. Abetment further requires proof of intentional aiding and active complicity; an uncorroborated co-noticee statement, absent recovery, CCTV, or independent-witness support, does not establish it. Failure to detect concealed currency during routine examination is insufficient. On these grounds, the penalty for abetment was set aside with consequential relief.
Electronic records relied on in customs penalty proceedings require prescribed certification, and an uncertified text-message printout has no evidentiary value where no forensic material links it to the alleged user. Such material cannot implicate a Customs officer in attempted illegal export of foreign currency. Abetment further requires proof of intentional aiding and active complicity; an uncorroborated co-noticee statement, absent recovery, CCTV, or independent-witness support, does not establish it. Failure to detect concealed currency during routine examination is insufficient. On these grounds, the penalty for abetment was set aside with consequential relief.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915