Mandatory textile export qualifiers distinguish flame-retardant fabrics from other listed fabrics for automated identification under the textiles ince...
Personal liberty safeguards restrict arrest after court-directed GST appearance, requiring interim release where authorities overreach pending proceed...
Alternative statutory remedy and delay bar GST writ challenges despite pending rectification, while distinct subject matter permits parallel proceedin...
Unverified Insight Portal Information Cannot Justify Reassessment Without a Verified Taxpayer-Specific Income-Escape Nexus or Demonstrated Application...
Page of 4913
Press 'Enter' after typing page number.
861 to 880 of 98250 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
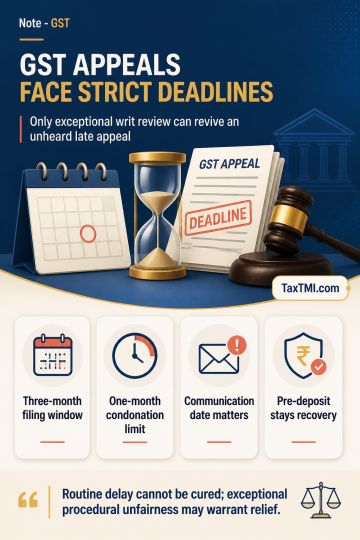
Section 107 of the CGST Act confines GST appeals to a three-month filing period, with condonation by the Appellate Authority limited to one further month upon sufficient cause. Section 5 of the Limitation Act cannot enlarge that statutory ceiling. Limitation runs from communication; portal availability and postal service under Section 169 may require factual scrutiny, while Rule 108 governs electronic or permitted manual filing where an order is unavailable on the portal. Statutory pre-deposit triggers a deemed stay of recovery for the balance demand. Article 226 may exceptionally restore an unheard appeal where defective communication, prompt action after knowledge and material procedural unfairness justify relief, but is not a routine cure for delay or inaction.
Section 107 of the CGST Act confines GST appeals to a three-month filing period, with condonation by the Appellate Authority limited to one further month upon sufficient cause. Section 5 of the Limitation Act cannot enlarge that statutory ceiling. Limitation runs from communication; portal availability and postal service under Section 169 may require factual scrutiny, while Rule 108 governs electronic or permitted manual filing where an order is unavailable on the portal. Statutory pre-deposit triggers a deemed stay of recovery for the balance demand. Article 226 may exceptionally restore an unheard appeal where defective communication, prompt action after knowledge and material procedural unfairness justify relief, but is not a routine cure for delay or inaction.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4913