Duplicate PAN allocation requires record verification and deactivation reasons before assessment-related transactions can be attributed to an assessee...
Faceless assessment safeguards require requested personal hearings and adequate final show-cause response time, failing which reassessment is required...
Embezzlement losses in charitable institutions remain allowable when misappropriation is established, irrecoverable, and not a specified-person benefi...
National long-distance undertaking status supports deduction where separately licensed infrastructure, resources, revenue, and expenditure establish c...
Agency reimbursement income follows contractual deposit-liability computation, while pending deposit collections do not constitute deemed-dividend loa...
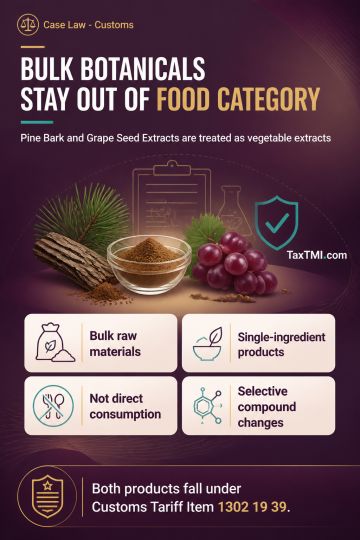
Pine Bark Extract and Grape Seed Extract are classified as vegetable extracts under Heading 1302 rather than as food preparations under Heading 2106. Multi-stage extraction, concentration, drying, or adsorption does not exclude goods from Heading 1302 unless processing selectively enriches or depletes particular compounds or compound classes beyond ordinary solvent extraction. As single-ingredient botanical extracts imported in bulk as raw materials, the products were not finished food or dietary supplements for direct consumption. Because neither product was specifically enumerated within Heading 1302, both fall under the residual tariff item for other vegetable extracts, Customs Tariff Item 1302 19 39.
Pine Bark Extract and Grape Seed Extract are classified as vegetable extracts under Heading 1302 rather than as food preparations under Heading 2106. Multi-stage extraction, concentration, drying, or adsorption does not exclude goods from Heading 1302 unless processing selectively enriches or depletes particular compounds or compound classes beyond ordinary solvent extraction. As single-ingredient botanical extracts imported in bulk as raw materials, the products were not finished food or dietary supplements for direct consumption. Because neither product was specifically enumerated within Heading 1302, both fall under the residual tariff item for other vegetable extracts, Customs Tariff Item 1302 19 39.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915