Government water works contract GST concession applied before its withdrawal, while contractual tax reimbursement claims lay outside advance-ruling sc...
Stamp valuation increases after registration-fee payment led to deletion of property-purchase addition within tolerance and without valuation referral...
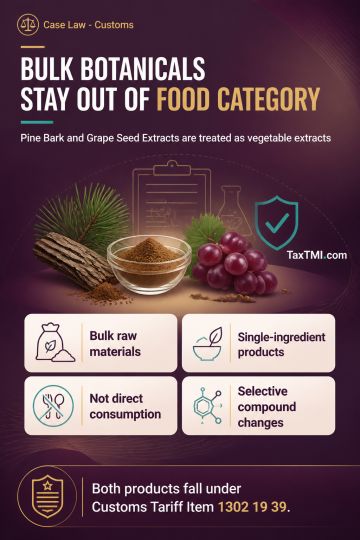
Pine Bark Extract and Grape Seed Extract are classified as vegetable extracts under Heading 1302 rather than as food preparations under Heading 2106. Multi-stage extraction, concentration, drying, or adsorption does not exclude goods from Heading 1302 unless processing selectively enriches or depletes particular compounds or compound classes beyond ordinary solvent extraction. As single-ingredient botanical extracts imported in bulk as raw materials, the products were not finished food or dietary supplements for direct consumption. Because neither product was specifically enumerated within Heading 1302, both fall under the residual tariff item for other vegetable extracts, Customs Tariff Item 1302 19 39.
Pine Bark Extract and Grape Seed Extract are classified as vegetable extracts under Heading 1302 rather than as food preparations under Heading 2106. Multi-stage extraction, concentration, drying, or adsorption does not exclude goods from Heading 1302 unless processing selectively enriches or depletes particular compounds or compound classes beyond ordinary solvent extraction. As single-ingredient botanical extracts imported in bulk as raw materials, the products were not finished food or dietary supplements for direct consumption. Because neither product was specifically enumerated within Heading 1302, both fall under the residual tariff item for other vegetable extracts, Customs Tariff Item 1302 19 39.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI