Factory-consumption condition restricts solar module parts exemption and excludes imported aluminium profiles fabricated outside the production factor...
Call-recording requirements for institutional-investor client communications become non-mandatory, while institutional-investor status adopts the exis...
Restricted silver imports may clear under a valid import authorisation without additional status or exchange-routing requirements unless expressly imp...
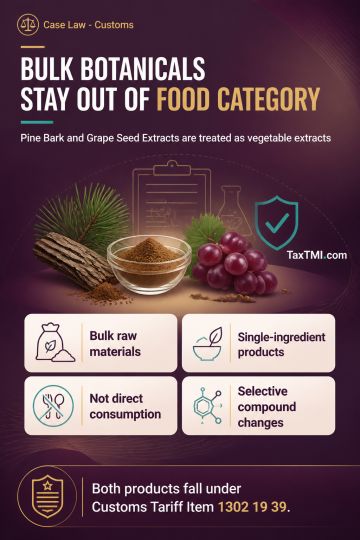
Pine Bark Extract and Grape Seed Extract are classified as vegetable extracts under Heading 1302 rather than as food preparations under Heading 2106. Multi-stage extraction, concentration, drying, or adsorption does not exclude goods from Heading 1302 unless processing selectively enriches or depletes particular compounds or compound classes beyond ordinary solvent extraction. As single-ingredient botanical extracts imported in bulk as raw materials, the products were not finished food or dietary supplements for direct consumption. Because neither product was specifically enumerated within Heading 1302, both fall under the residual tariff item for other vegetable extracts, Customs Tariff Item 1302 19 39.
Pine Bark Extract and Grape Seed Extract are classified as vegetable extracts under Heading 1302 rather than as food preparations under Heading 2106. Multi-stage extraction, concentration, drying, or adsorption does not exclude goods from Heading 1302 unless processing selectively enriches or depletes particular compounds or compound classes beyond ordinary solvent extraction. As single-ingredient botanical extracts imported in bulk as raw materials, the products were not finished food or dietary supplements for direct consumption. Because neither product was specifically enumerated within Heading 1302, both fall under the residual tariff item for other vegetable extracts, Customs Tariff Item 1302 19 39.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915