Stamp valuation increases after registration-fee payment led to deletion of property-purchase addition within tolerance and without valuation referral...
Capital Asset Conversion Requires Proven Business Stock Treatment; Paper Consideration in Spousal Flat Transfers Does Not Create Taxable Business Inco...
Human-probability test defeats political donation deduction where banking records mask accommodation-entry fund layering and evidence shows non-genuin...
Page of 4920
Press 'Enter' after typing page number.
1121 to 1140 of 98394 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
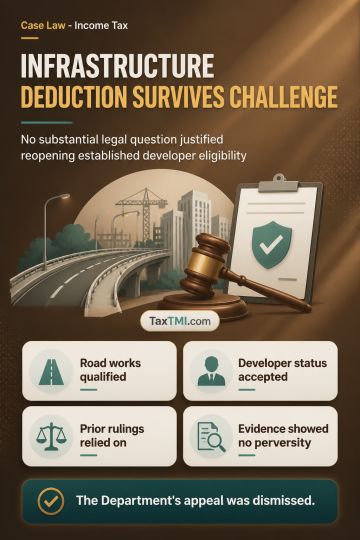
Section 260-A permits a High Court appeal only where a substantial question of law arises; it does not allow reappreciation of evidence or replacement of concurrent factual findings. Concurrent findings that road and infrastructure works qualified the assessee as a developer eligible for deduction under section 80-IA(4) were based on the record, with no perversity or erroneous legal test shown. Reliance on a previously confirmed Tribunal order and dismissal of a similar appeal for another assessment year did not create a substantial question of law. The Department's appeal was dismissed.
Section 260-A permits a High Court appeal only where a substantial question of law arises; it does not allow reappreciation of evidence or replacement of concurrent factual findings. Concurrent findings that road and infrastructure works qualified the assessee as a developer eligible for deduction under section 80-IA(4) were based on the record, with no perversity or erroneous legal test shown. Reliance on a previously confirmed Tribunal order and dismissal of a similar appeal for another assessment year did not create a substantial question of law. The Department's appeal was dismissed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4920