Centralised assessment transfers: participation after requesting centralisation can bar technical jurisdictional challenges, while assessment disputes...
Binding precedent remains operative despite pending challenge, supporting deletion of interest disallowance when debt is converted into preference sha...
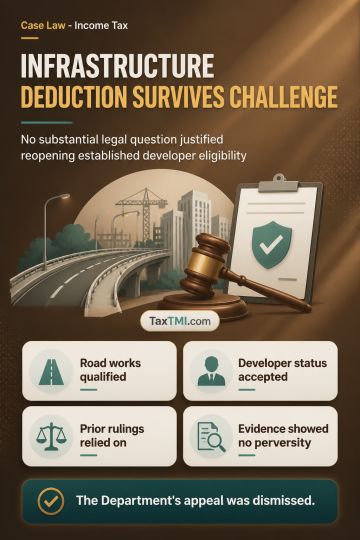
Section 260-A permits a High Court appeal only where a substantial question of law arises; it does not allow reappreciation of evidence or replacement of concurrent factual findings. Concurrent findings that road and infrastructure works qualified the assessee as a developer eligible for deduction under section 80-IA(4) were based on the record, with no perversity or erroneous legal test shown. Reliance on a previously confirmed Tribunal order and dismissal of a similar appeal for another assessment year did not create a substantial question of law. The Department's appeal was dismissed.
Section 260-A permits a High Court appeal only where a substantial question of law arises; it does not allow reappreciation of evidence or replacement of concurrent factual findings. Concurrent findings that road and infrastructure works qualified the assessee as a developer eligible for deduction under section 80-IA(4) were based on the record, with no perversity or erroneous legal test shown. Reliance on a previously confirmed Tribunal order and dismissal of a similar appeal for another assessment year did not create a substantial question of law. The Department's appeal was dismissed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915