Transfer-pricing comparability filters require fresh arm's-length analysis, while delayed receivables need separate reconsideration with working-capit...
Section 153C jurisdiction requires timely deemed search and assessee-specific satisfaction material; otherwise reassessment must use the proper statut...
Credit-note turnover adjustments preserve inverted-duty refunds, while ministerial re-computation does not constitute an impermissible appellate reman...
Page of 4915
Press 'Enter' after typing page number.
1161 to 1180 of 98288 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
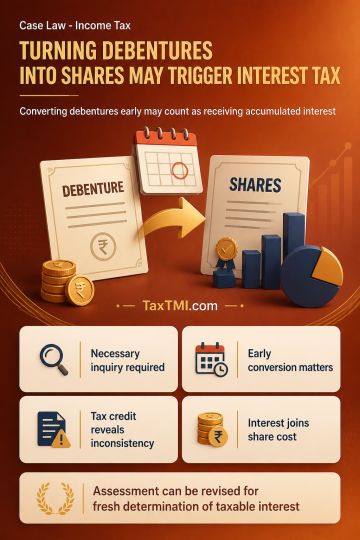
Revisionary jurisdiction applies where a reassessment accepts non-taxability of accumulated interest without necessary inquiry or application of governing provisions, rendering it erroneous and prejudicial to Revenue interests and permitting fresh determination. Premature conversion of zero-coupon debentures into equity shares of ascertainable value can constitute constructive receipt of accumulated interest even under cash-basis accounting. Claiming tax-deducted-at-source credit for that interest is inconsistent with denying the underlying income. The capital-gains exclusion for conversion does not exempt embedded interest from taxation; once taxed, the interest forms part of the shares' cost basis, preventing double taxation on sale.
Revisionary jurisdiction applies where a reassessment accepts non-taxability of accumulated interest without necessary inquiry or application of governing provisions, rendering it erroneous and prejudicial to Revenue interests and permitting fresh determination. Premature conversion of zero-coupon debentures into equity shares of ascertainable value can constitute constructive receipt of accumulated interest even under cash-basis accounting. Claiming tax-deducted-at-source credit for that interest is inconsistent with denying the underlying income. The capital-gains exclusion for conversion does not exempt embedded interest from taxation; once taxed, the interest forms part of the shares' cost basis, preventing double taxation on sale.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915