Duplicate PAN cancellation timeframe requires prior administrative representation before judicial intervention, ensuring a time-bound decision on the ...
Natural justice and pre-CIRP labour awards protect termination compensation, permitting withdrawal of court deposits despite later insolvency resoluti...
Arbitration of SEZ sub-lease monetary claims preserves rent, maintenance, termination, improvements and damages disputes while unused premises are vac...
Scientific research approval grants a research association tax recognition, subject to annual donor reporting, certification, and regulatory complianc...
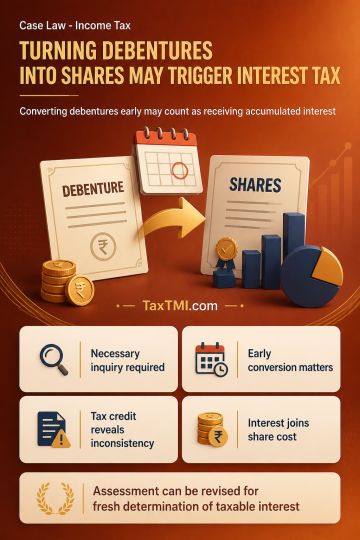
Revisionary jurisdiction applies where a reassessment accepts non-taxability of accumulated interest without necessary inquiry or application of governing provisions, rendering it erroneous and prejudicial to Revenue interests and permitting fresh determination. Premature conversion of zero-coupon debentures into equity shares of ascertainable value can constitute constructive receipt of accumulated interest even under cash-basis accounting. Claiming tax-deducted-at-source credit for that interest is inconsistent with denying the underlying income. The capital-gains exclusion for conversion does not exempt embedded interest from taxation; once taxed, the interest forms part of the shares' cost basis, preventing double taxation on sale.
Revisionary jurisdiction applies where a reassessment accepts non-taxability of accumulated interest without necessary inquiry or application of governing provisions, rendering it erroneous and prejudicial to Revenue interests and permitting fresh determination. Premature conversion of zero-coupon debentures into equity shares of ascertainable value can constitute constructive receipt of accumulated interest even under cash-basis accounting. Claiming tax-deducted-at-source credit for that interest is inconsistent with denying the underlying income. The capital-gains exclusion for conversion does not exempt embedded interest from taxation; once taxed, the interest forms part of the shares' cost basis, preventing double taxation on sale.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918